
Contribution Margin & Break-Even Analysis in Cases
Can a business grow faster and become less profitable with every extra sale? Yes - if each order adds too little contribution after variable costs, growth simply pushes more volume through a weak economic engine.
- Contribution margin is revenue minus variable cost. It tells you how much each unit contributes to fixed cost and profit.
- Break-even volume = Fixed costs / Contribution margin per unit.
- Break-even revenue = Fixed costs / Contribution margin ratio.
- Margin of safety shows how far actual sales are above break-even. Higher is safer.
- In cases, separate fixed costs, variable costs and step costs before calculating anything.
- The best case answer is not “increase volume.” It is “increase profitable volume where contribution margin is positive and scalable.”
Big Picture
Contribution margin is the bridge between unit economics and total profitability. It answers one brutal question: after serving one more customer, how much money is left to pay for the business machine?
Core Explanation: The Logic You Must See
Every case involving break-even analysis has two layers:
- Unit economics: Does each unit sold create contribution?
- Scale economics: Is total contribution large enough to cover fixed costs?
If contribution margin per unit is positive, volume helps. If it is zero, volume does nothing. If it is negative, volume destroys profit.
Before using formulas, classify costs correctly. If this part feels shaky, revise fixed, variable and step costs first - most wrong break-even answers begin with wrong cost classification.
The Four Formulas That Run Most Cases
A Small Worked Example
Assume a D2C snack brand sells one pack at ₹100. Variable cost per pack is ₹60, including ingredients, packaging, payment gateway and delivery-linked cost. Monthly fixed cost is ₹4,00,000.
The case insight is simple: selling 8,000 packs is not “almost profitable” emotionally; it is still 2,000 packs short of break-even mathematically.
The Break-Even Decision Matrix
Once you calculate contribution margin, do not stop. Map the business by volume and contribution margin. This tells you where to push growth and where to fix the economics first.
This matrix is especially useful in product portfolio, restaurant, airline, retail and SaaS cases. A high-volume product with weak contribution can look impressive in revenue but quietly consume capacity, discounts and management attention.
Metrics to Track in Break-Even Cases
There is no universal “good” contribution margin across industries. A SaaS company, an airline seat, a cloud kitchen order and a cement bag have different cost structures. So the correct answer is: calculate the metric, compare it with competitors or internal segments, then judge whether the number is strong.
Definitions
- Contribution margin: Revenue minus variable costs; the amount available to cover fixed costs and profit.
- Variable cost: A cost that changes directly with output or activity volume.
- Fixed cost: A cost that remains unchanged within a relevant activity range.
- Break-even point: The sales level where total revenue equals total cost and profit is zero.
- Margin of safety: The excess of actual or expected sales over break-even sales.
The Five-Step Case Method
Case Study: Rebel Foods and the Cloud Kitchen Break-Even Logic
Rebel Foods is a useful case because cloud kitchens make contribution margin visible: each order must cover food, packaging, delivery-linked costs and then help absorb kitchen-level fixed costs.
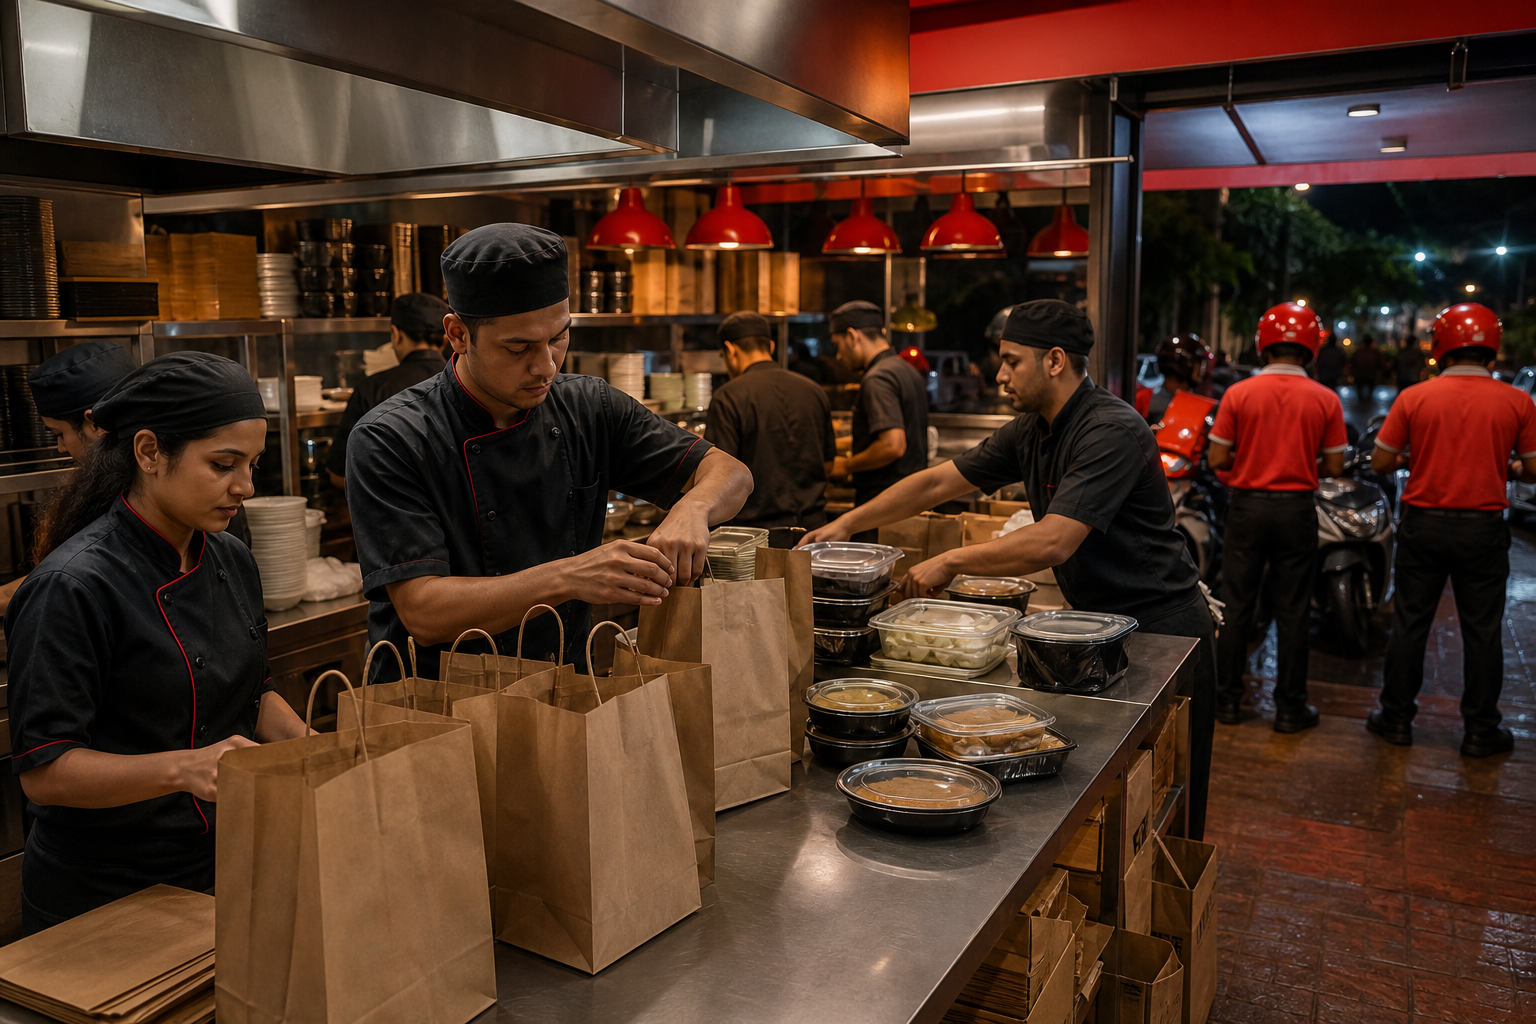
Situation: A traditional restaurant depends on location, seating capacity and dine-in experience. A cloud-kitchen-led model changes the economics: the kitchen becomes the operating asset, and multiple virtual food brands can potentially use the same kitchen infrastructure.
The move: Rebel Foods built a model around shared kitchen capacity and multiple cuisine brands rather than one dine-in outlet format. In contribution margin terms, the move tries to increase total contribution per kitchen by running more orders through the same fixed-cost base.
Why it matters: The primary driver is better utilization of shared kitchen fixed costs. Supporting drivers include menu standardization, brand portfolio breadth, demand pooling across cuisines, delivery-platform operations and tighter kitchen-level process control. It is not simply “cloud kitchens have lower rent.” The model works only if order-level contribution is positive and demand is dense enough to cover kitchen fixed costs.
Lesson: Break-even analysis is not just a finance formula. It explains the operating model. In Rebel Foods-like businesses, a manager should ask, “Which brand, meal occasion and kitchen cluster creates the highest contribution after variable costs?”
How AI Changes Contribution Margin & Break-Even Analysis
AI does not replace the formula. It improves the inputs and speeds up scenario testing.
- Better demand forecasting: ML models can estimate how volume changes if price, discount, delivery fee or menu mix changes. This makes break-even less static.
- Dynamic contribution analysis: AI can track contribution by SKU, channel, geography and customer cohort, revealing hidden “scale traps” where revenue grows but contribution stays weak.
- Scenario simulation: Teams can test “what if fixed costs rise,” “what if discounts fall,” or “what if variable cost per unit improves” before committing to an expansion plan.
Use ChatGPT or Claude to build a sensitivity table: give it price, variable cost, fixed cost and three demand scenarios, then ask it to calculate break-even units, margin of safety and the recommendation. For deeper prep, use the same workflow after revising how to pressure-test a profitability hypothesis with AI.
Interview Relevance
“A food delivery brand is growing orders rapidly but still losing money. How would you check whether it can break even?”
Always say the decision rule aloud: “If contribution margin is negative, more volume worsens losses; if positive, we then check whether achievable volume exceeds break-even.”
Common Mistake
The biggest mistake is treating all costs as variable or all costs as fixed. It ruins the break-even number and leads to bad recommendations. One-line fix: first classify costs by how they behave with volume, then calculate contribution margin.