
Decomposing Cost: Fixed, Variable & Step Costs
A restaurant founder looks at the monthly P&L and sees losses rising even as orders grow. The trap is hidden in plain sight: rent did not change, packaging moved with every order, and one extra night shift made cost jump like a staircase.
- Fixed costs stay constant in total within a relevant range, such as rent, salaried staff or software subscriptions.
- Variable costs move with volume, such as raw material, delivery fee per order or payment gateway charges.
- Step costs stay flat for a capacity band, then jump when you add a shift, machine, store, warehouse or team.
- Always define the cost driver: orders, kilometres, rooms occupied, consulting hours, units produced or customers served.
- Unit cost can mislead: fixed cost per unit falls as volume rises, but step cost can suddenly push it back up.
- The best interview answer separates behaviour, driver, relevant range and managerial action.
Big Picture: Cost Is a Stack, Not a Single Number
Cost decomposition means splitting total cost by how each component behaves when activity changes. The same expense can behave differently depending on the time horizon and the cost driver, so never label a cost without context.
Core Explanation: The Three Cost Behaviours
Fixed cost is the committed base. If a warehouse pays the same rent whether it ships 10,000 or 12,000 parcels this month, rent is fixed within that range. But it is not fixed forever: add another warehouse and the rent base changes.
Variable cost is the cost that moves with each unit of activity. For a food delivery order, ingredients, packaging and certain platform-linked charges usually rise as orders rise. The managerial question is: does variable cost per unit stay stable, fall with scale, or rise due to inefficiency?
Step cost is the interview differentiator. It behaves like fixed cost for a while, then jumps when capacity is exhausted. A second supervisor, an extra truck, another customer-support pod or a new dark store can create a cost step.
The One Concept That Prevents Bad Answers: Relevant Range
The relevant range is the activity band where a cost behaviour assumption holds. Rent may be fixed between 1,000 and 5,000 orders a day. Beyond that, you may need a second kitchen, second shift or larger facility, and the cost becomes a step.
This is why “fixed cost per unit falls with volume” is true only until the next capacity step. In case interviews, this is where strong candidates show business judgment.
Metrics to Track When Decomposing Cost
Do not stop at labels. Convert the decomposition into measures that help management decide whether to cut, renegotiate, automate, price differently or scale volume.
Worked Example: When Growth Still Hurts Profit
Take a hypothetical cloud-kitchen month. The kitchen has fixed monthly cost of ₹4,00,000. Variable cost is ₹120 per order. Average revenue is ₹220 per order, so contribution margin is ₹100 per order. If monthly orders cross 5,000, the kitchen needs an extra shift supervisor and utilities costing ₹1,00,000 per month.
The lesson: volume improved profit, but not as much as a simple fixed-variable model would predict. The step cost absorbed part of the scale benefit.
Definitions You Can Say in One Breath
- Fixed cost: A cost that stays constant in total within the relevant range.
- Variable cost: A cost that changes in total in proportion to activity volume.
- Step cost: A cost that stays flat over a range, then jumps at a capacity threshold.
- Cost driver: The activity that causes a cost to change.
- Relevant range: The activity band where the assumed cost behaviour remains valid.
These are standard managerial accounting cost-behaviour concepts; OpenStax explains the same fixed, variable and mixed-cost logic in its chapter on basic cost behavior patterns.
Case Study: Rebel Foods and the Economics of Shared Kitchen Capacity
Rebel Foods is useful for cost decomposition because its cloud-kitchen model makes fixed capacity, variable order cost and step expansion visible in one business.
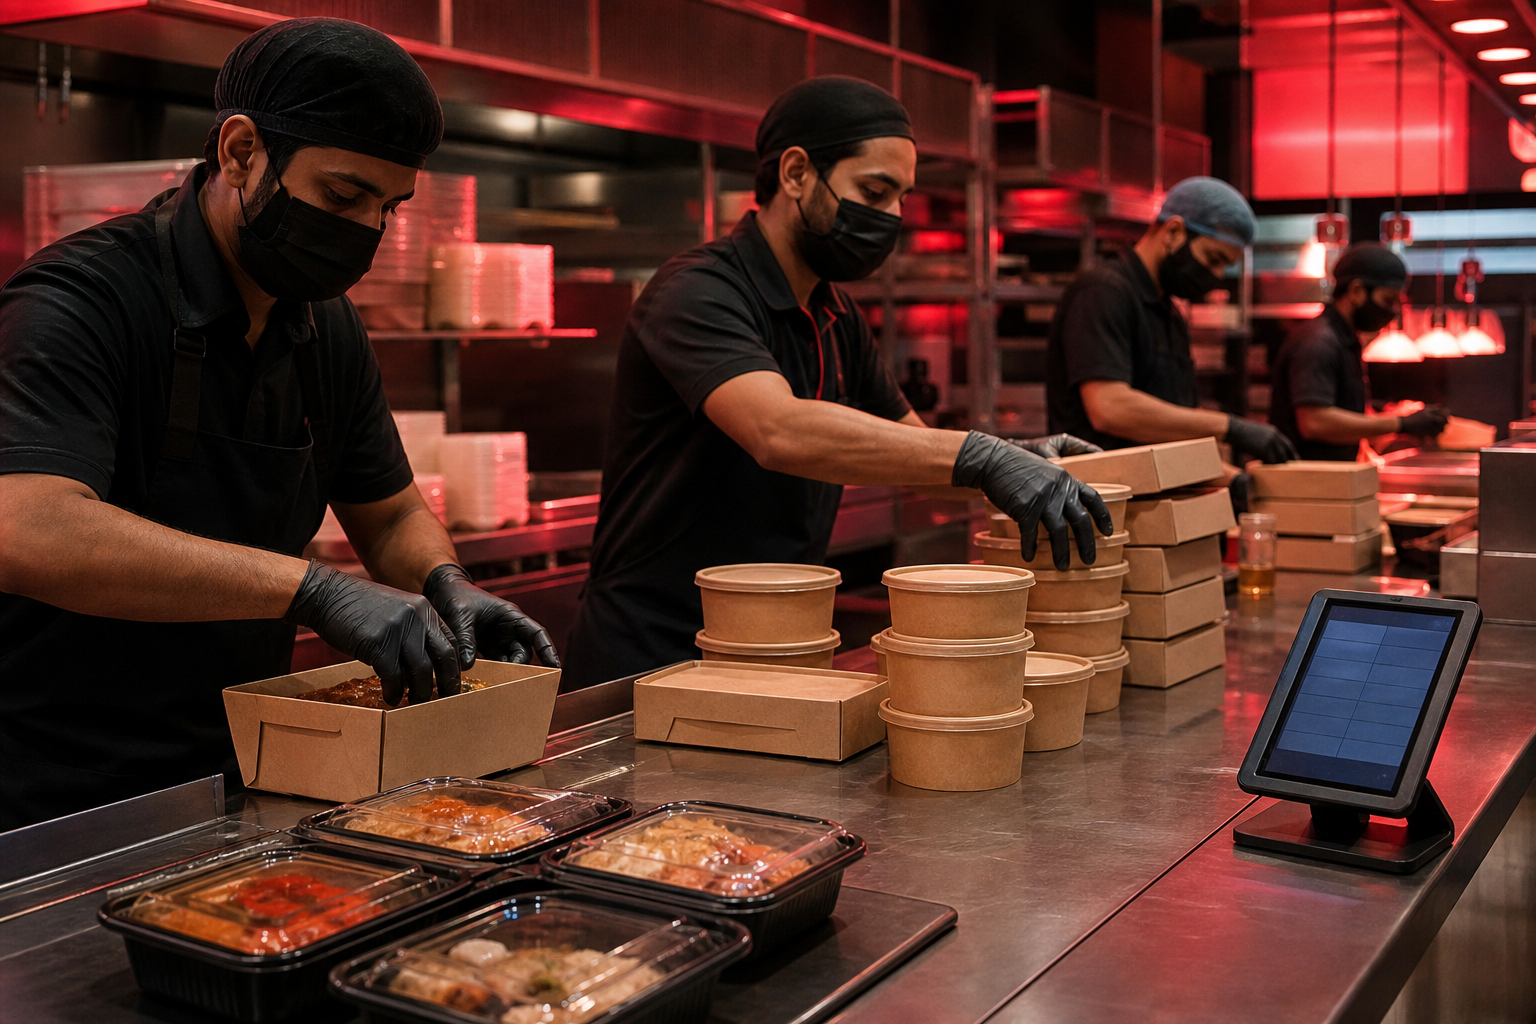
Rebel Foods operates digital-first food brands through cloud kitchens rather than relying only on traditional dine-in restaurants. That makes it a strong Indian example for this topic: the company has to manage kitchen-level fixed costs, brand-level demand, order-level variable costs and capacity steps as volumes change.
Situation: In a traditional restaurant, revenue is tied to dine-in capacity, location and cuisine identity. A cloud-kitchen model separates food production from dine-in real estate and allows multiple food brands to use shared kitchen infrastructure.
The move: The primary driver is shared kitchen capacity. A single kitchen can support multiple digital brands, so fixed assets such as kitchen space, equipment and local operations management can be spread across more demand pools. Supporting drivers include standardized recipes, central procurement, data-led menu decisions and delivery-led demand generation.
The lesson: Cost decomposition helps explain why the model can scale, but also where it can break. If order volume rises within existing kitchen capacity, fixed cost per order falls. If volume crosses the kitchen’s limit, new shifts, equipment or kitchens create step costs. If ingredients, packaging or delivery-linked costs rise faster than revenue per order, growth may still dilute margins.
How AI Changes Decomposing Cost
1. AI separates mixed costs faster. Many real costs are mixed, not pure fixed or variable. Machine learning can help estimate how utilities, support tickets, delivery exceptions or labour hours change with volume, seasonality and service levels.
2. AI detects cost steps before they hit the P&L. Forecasting tools can flag when order volume, machine hours, warehouse throughput or call volumes are approaching a capacity threshold. This helps teams plan whether to add capacity, smooth demand or redesign operations.
3. AI improves variance explanation. Instead of saying “cost increased because volume increased,” AI-assisted analysis can decompose the variance into price effect, volume effect, mix effect, productivity effect and capacity-step effect.
Use ChatGPT or Claude on a case prompt like this: “Act as a consulting manager. Given this cost list, classify each item as fixed, variable, step or mixed, state the cost driver, relevant range and one management action.” Then challenge the output by asking: “Which classifications could change if volume doubles?”
Interview Relevance
“A food delivery company is growing orders, but profitability is worsening. How would you decompose its costs and identify the issue?”
This is a core consulting-style diagnostic: you are not just doing accounting, you are turning cost behaviour into a management decision. If you want the broader context of how consultants structure such analyses into workstreams, revise what a consultant does week to week.
Say “within the relevant range” whenever you call something fixed. It signals that you understand capacity, not just definitions.
Common Mistake
The biggest mistake is treating fixed costs as fixed forever and ignoring step costs. That leads to wrong break-even math and weak recommendations. One-line fix: define the cost driver, state the relevant range, then ask what capacity threshold changes the cost.