
A Cost Transformation Programme, Broken Down
A CFO does not wake up worried because “costs are high.” She worries because costs are growing faster than revenue, customers still expect better service, and a blunt hiring freeze could damage the very teams that create growth.
That is why cost transformation is one of the most misunderstood consulting topics: the amateur answer cuts line items; the strong answer redesigns the cost system.
- Cost transformation is a structured reset of the cost base, operating model and behaviours - not a one-time budget cut.
- The core sequence is: baseline costs, diagnose drivers, design levers, implement with owners, and sustain through governance.
- Always separate structural savings from one-off savings; interviewers reward candidates who ask whether savings recur.
- The best levers usually sit in procurement, process productivity, organisation design, footprint, product complexity and demand management.
- Use a 2x2 to prioritise ideas by impact and ease of implementation; do not recommend everything at once.
- Track hard metrics: cost-to-income ratio, EBITDA margin, procurement savings, FTE productivity, cost-to-serve and run-rate savings.
- The biggest trap is a flat “cut 10% everywhere” answer; the fix is to protect growth-critical capabilities while attacking waste.
Big Picture
A cost transformation programme has one job: make the organisation structurally cheaper to run without weakening the customer promise or growth engine. Think of it as moving from “spend less this quarter” to “operate differently every quarter.”
Core Explanation: What Actually Happens in a Cost Transformation
The consulting-grade way to break down a cost transformation is to start with the cost baseline, not with ideas. A baseline maps current cost by business unit, function, product, location, vendor, channel and activity. Without it, savings are guesses.
Then you identify cost drivers - the factors that cause cost to rise or fall. For example, delivery cost may be driven by order density, batching, route length, return rate and rider utilisation. Salary cost may be driven by spans of control, layers, overtime, attrition and automation level.
The strongest answers also distinguish between three types of cost:
- Fixed cost: cost that does not move quickly with volume, such as rent or core management salaries.
- Variable cost: cost that moves with volume, such as packaging, commissions or delivery payouts.
- Semi-variable cost: cost with both fixed and variable elements, such as call-centre staffing or cloud infrastructure.
If you need a refresher on the unit-economics side of this logic, revise contribution margin and break-even analysis in cases before attempting a cost transformation case.
The Cost Transformation Lever Map
Cost levers are not random suggestions. They normally fall into six buckets. A good candidate names the bucket, explains the mechanism, and flags the risk.
Notice the consultant’s mindset: every lever has a benefit and a trade-off. If your answer only says “reduce headcount,” it sounds like cost cutting. If it says “simplify low-value work, automate repeatable tasks, redesign spans and protect revenue-facing capacity,” it sounds like cost transformation.
The 2x2 Prioritisation Matrix
A real programme will generate dozens of ideas. The issue is not whether savings exist; the issue is what to do first. Use impact versus ease to sequence the programme.
- Big wins: high impact, easy enough to execute - ideal first-wave initiatives.
- Strategic bets: high impact but hard - usually require leadership sponsorship, systems, negotiations or restructuring.
- Quick fixes: lower impact but easy - useful for momentum and funding larger work.
- Defer: low impact and hard - do not waste senior attention here.
This is where many candidates become too theoretical. If the company is a manufacturer, work through materials, yield loss, plant utilisation and logistics. If it is a services business, work through staffing pyramid, utilisation, bench, automation and pricing discipline. For practice, compare this logic with a services business with rising costs or a manufacturer whose margins have fallen.
Metrics: How to Know the Programme Is Working
Cost transformation must be measurable. But the right metric depends on the business model. A bank, airline, SaaS company, retailer and manufacturer will not use the same benchmark. In interviews, state the formula and say you would compare it against historical trend, peer benchmark and service outcomes.
Do not track savings alone. Pair every cost metric with a guardrail: customer NPS or complaints, defect rate, on-time delivery, attrition, safety, risk incidents or revenue retention. That is the difference between a sustainable programme and a spreadsheet exercise.
Worked Example: Turning a Cost Target into Real Levers
Suppose a B2B services company has annual revenue of ₹200 crore and operating cost of ₹170 crore. EBITDA is therefore ₹30 crore, so EBITDA margin is 15%.
Leadership wants a ₹15 crore recurring saving. A weak answer says “cut 9% of costs.” A better answer builds a savings bridge:
The new cost base becomes ₹155 crore. EBITDA rises from ₹30 crore to ₹45 crore, and EBITDA margin improves from 15% to 22.5%, assuming revenue is protected. The final phrase matters: assuming revenue is protected. If the cost actions damage delivery quality and revenue falls, the transformation has failed.
Definitions You Must Be Able to Say Clearly
- Cost transformation: A structured reset of cost, operating model and behaviours to deliver recurring savings without weakening strategy.
- Cost driver: A factor that directly causes a cost to increase or decrease.
- Run-rate saving: The annualised recurring value of a saving after it has been implemented.
- One-off saving: A non-recurring benefit, such as delayed hiring, asset sale or temporary spend freeze.
- Cost-to-serve: The total cost of serving a specific customer, segment, channel or order type.
- Zero-based budgeting: A budgeting approach where spend must be justified from zero rather than rolled forward from last year.
If consulting vocabulary itself feels shaky, use the consulting terms glossary to revise words like baseline, synergies, workstream, run-rate and implementation roadmap.
Case Study: IndiGo and the Cost Advantage Operating Model
IndiGo shows that the most powerful cost transformation is often not a temporary programme, but an operating model designed to keep unit costs structurally low.
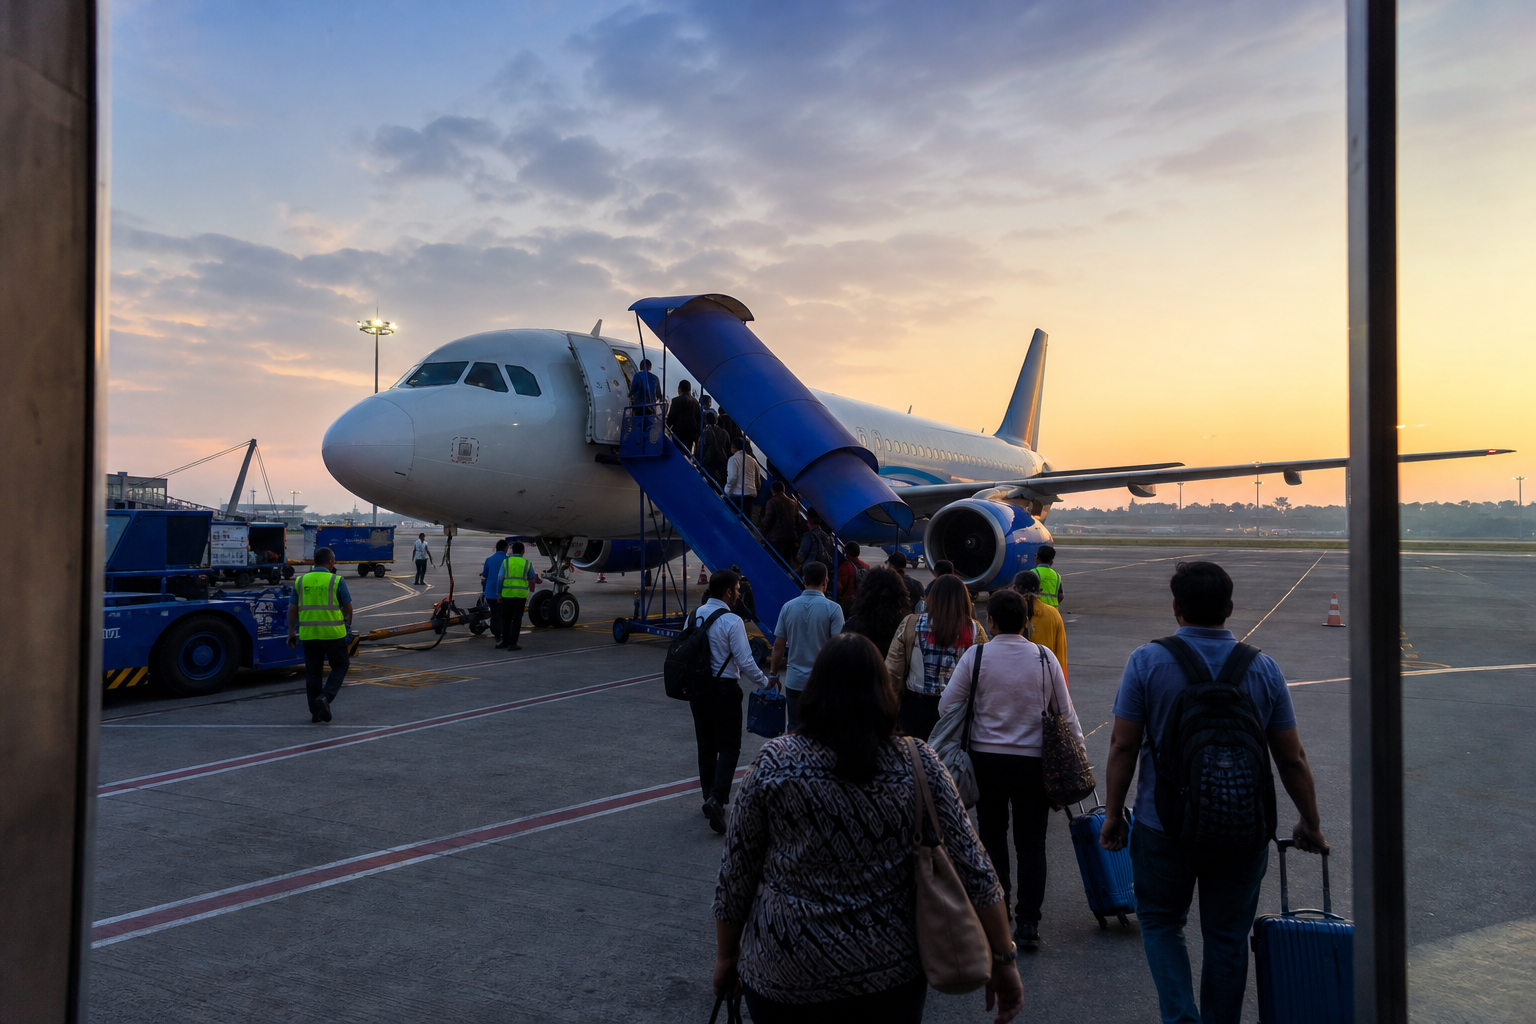
Situation: Indian aviation is price-sensitive, operationally complex and exposed to fuel, currency, airport and utilisation pressures. In such a market, a carrier cannot rely only on premium pricing; it needs a cost position that survives fare competition.
The move: IndiGo built its advantage around a simplified low-cost operating model. The primary driver was operational standardisation - especially a narrow aircraft family and disciplined operating routines. Supporting drivers included fast turnarounds, high aircraft utilisation, dense domestic network planning, direct distribution discipline, simple service design and tight control of controllable overheads.
The lesson: IndiGo’s cost advantage is not explained by one magic lever. It is a system. Standardisation reduces complexity; faster turnarounds improve asset productivity; simple service design reduces process load; route density supports utilisation. That is exactly how a cost transformation should be explained in interviews - as connected operating choices, not isolated cuts.
So what: In a cost transformation case, do not jump straight to layoffs or vendor renegotiation. Ask what operating model the company is trying to win with, then remove cost that does not support that model.
How AI Changes Cost Transformation
AI is changing cost transformation in three concrete ways.
- Faster cost baselining: AI-assisted analytics can classify spend, detect duplicate vendors, flag unusual invoices and cluster expenses by supplier, location or business unit. This makes the first diagnostic phase faster and less dependent on manual Excel cleaning.
- Process mining plus automation: AI tools can identify repetitive workflows, exception-heavy processes and approval bottlenecks. The value is not “automate everything”; it is to redesign the process first, then automate the stable parts.
- Smarter workforce and demand planning: Forecasting models can help align staffing, inventory, routes, call-centre capacity or cloud resources to demand. This reduces waste caused by overcapacity while protecting service levels.
Use NotebookLM like a consulting case room: upload a company annual report, recent investor presentation and your cost transformation notes, then ask it to generate a cost baseline hypothesis, likely cost drivers, five interview questions and risks to each savings lever.
The caution: AI can surface opportunities, but management still owns the trade-offs. A model may recommend reducing support staff; a consultant must ask whether that will raise churn, defects, compliance risk or employee burnout.
Interview Relevance
“Our client’s operating costs have grown faster than revenue for three years. The CEO wants a cost transformation programme. How would you structure the work?”
When recommending savings, explicitly say what you will not cut: sales capacity in a growth market, risk controls in a regulated business, safety in operations, or core product capability. This signals business judgment.
For a deeper version of this exact judgment, revise recommending cost reduction without killing growth.
Common Mistake
The single biggest mistake is recommending a flat percentage cut across all departments. It costs candidates because it ignores cost drivers, strategic priorities and implementation risk. The one-line fix: cut waste by driver, protect capabilities by strategy.