
Government Capital Spending and the Sectors It Pulls
The common mistake is to imagine government capital spending as a highway ribbon-cutting photo. In reality, one public project can trigger a chain of steel orders, cement dispatches, equipment financing, logistics contracts, labour hiring and finally private capex.
- Government capex is public spending that creates long-lived assets such as roads, railways, ports, power assets, defence equipment and digital infrastructure.
- The first pull is direct: contractors, EPC firms, capital goods, rail, defence, power equipment and construction materials.
- The second pull is indirect: steel, cement, chemicals, logistics, banks, NBFCs, staffing and industrial services.
- The third pull is induced demand: wages, local services, consumption and private investment when confidence improves.
- The interview answer must trace the chain: budget outlay - tender - order book - execution - cash flow - sector earnings.
- Track six signals: capex growth, capex share of spending, tendering pace, order book cover, book-to-bill ratio and working-capital cycle.
- The trap: saying “infrastructure benefits” without separating early-cycle winners from late-cycle beneficiaries.
Big Picture: Government Capex Is a Demand Flywheel
Government capital spending works like a flywheel. The state spends because private demand is weak, infrastructure is inadequate, or strategic capacity is needed. If execution is strong, that spending raises orders and incomes, which can later crowd in private investment.
Core Explanation: The Three Pulls of Government Capital Spending
Think of government capex in three rings. The centre is the public project. The next ring is the companies that build or supply it. The outer ring is the wider economy that benefits from better infrastructure, higher incomes and improved confidence.
1. Direct Pull: Who Gets the First Orders?
The first winners are the firms closest to project award and execution. These include EPC contractors, road developers, rail equipment makers, metro suppliers, power transmission companies, defence manufacturers, civil construction firms and project management consultants.
This is why infrastructure-linked recruiters often test whether you understand the chemicals, metals and industrials teardown: public capex quickly becomes a question of order books, material cost, capacity and execution risk.
2. Supplier Pull: Who Benefits Behind the Contractor?
Behind every public project sits a supplier stack. Roads pull cement, bitumen, aggregates, steel, tyres and construction equipment. Railways pull coaches, wagons, signalling, bearings, cables and fabricated metal. Power transmission pulls towers, conductors, transformers, insulators and engineering services.
For chemicals, metals and industrial companies, government demand matters because policy, infrastructure and industrial incentives often shape plant location, capacity utilisation and pricing power. If you want the policy angle in more detail, revise government policy and incentives in chemicals, metals and industrials.
3. Finance Pull: Who Funds the Working Capital?
Public projects create financing needs before they create profits. Contractors must buy materials, mobilise labour, submit performance guarantees and wait for milestone payments. That pulls banks, NBFCs, equipment financiers, insurers and guarantee providers into the chain.
This is why a strong capex cycle can still hurt a weak contractor: orders may rise, but receivables and debt can rise faster if payments are delayed.
4. Productivity Pull: What Changes After the Asset Is Built?
The deeper benefit appears after completion. Better roads reduce transit time. Ports improve export competitiveness. Rail freight capacity reduces logistics bottlenecks. Digital infrastructure improves connectivity and service delivery.
For example, telecom and digital infrastructure capex can pull fibre, towers, data centres, power backup, enterprise connectivity and cloud-linked services. For that sector-specific chain, revise government policy shaping telecom and digital infrastructure.
The Budget-to-Earnings Transmission Map
In interviews, do not jump from “government announced capex” to “companies will grow.” The market rewards execution, not announcement. A clean answer follows the transmission path below.
Key Metrics to Track: Capex Pull Is Measured, Not Assumed
Use these measures to sound like a manager, not a headline reader. The “good number” is a practical interview heuristic; always compare it with the sector’s history and peer set.
Definitions You Should Be Able to Say in One Breath
- Government capital expenditure: Public spending that creates long-lived assets or capacity, such as roads, railways, power systems or defence equipment.
- Revenue expenditure: Government spending for current operations, salaries, subsidies, interest and maintenance, without directly creating a durable asset.
- Multiplier effect: The total increase in income or output created by an initial increase in spending.
- Crowding in: Public investment encouraging private investment by improving demand visibility, infrastructure or confidence.
- Order book: Contracted future revenue not yet executed or billed.
Sector Map: Who Benefits Early, Who Benefits Late?
Early-cycle beneficiaries get orders as soon as projects are awarded. Late-cycle beneficiaries gain when the completed asset improves productivity, mobility or demand. This distinction is where strong candidates separate themselves.
BEML: A Public Capex Pull Story Beyond Roads
BEML shows how government capex can pull a manufacturing company through rail, metro, defence, mining and construction equipment demand.
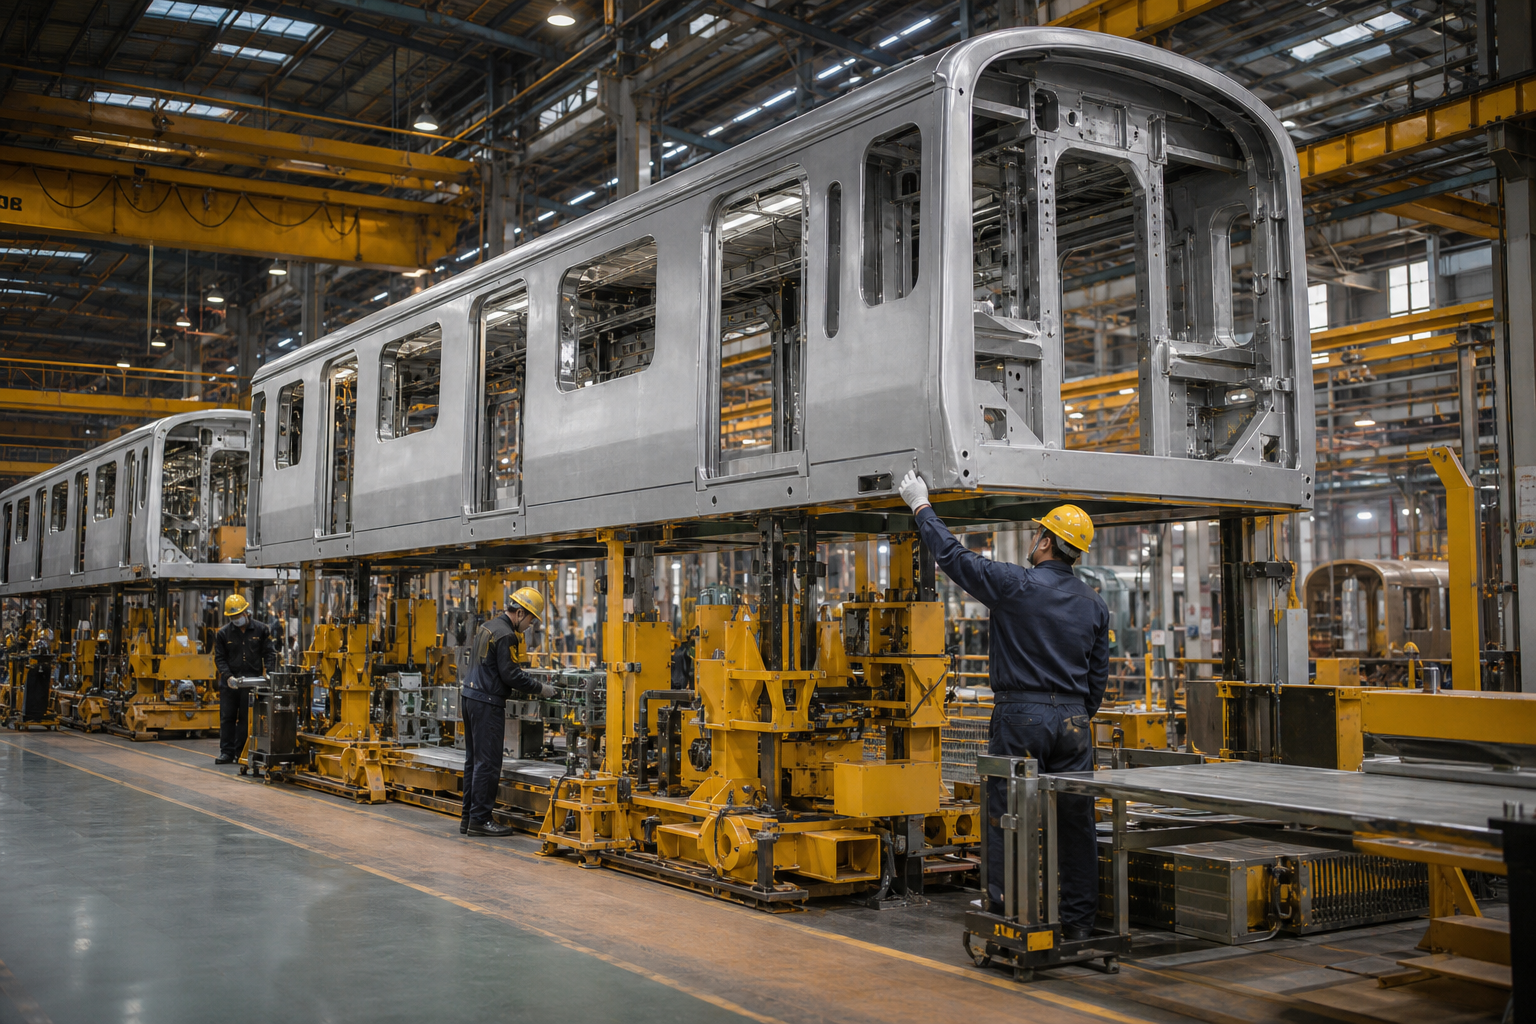
Situation. Many students think government capex mainly benefits road contractors. BEML is a useful counterexample because it sits in multiple public-investment-linked pools: rail and metro mobility, defence mobility, mining equipment and construction equipment.
The move. Instead of depending on a single infrastructure theme, BEML’s model links to several public procurement streams. Rail and metro capex can pull rolling stock and components. Defence modernisation can pull specialised mobility equipment. Mining and construction activity can pull heavy machinery and spares.
The primary driver. The main driver is exposure to multi-year public procurement and infrastructure creation. The supporting drivers are manufacturing capability, qualification for complex tenders, after-sales service, localisation, vendor development and the ability to manage long working-capital cycles.
The lesson. A government capex beneficiary is not automatically a good business. The investment thesis depends on order visibility, execution discipline, margins, receivables and whether the company can convert public demand into cash profits.
How AI Changes Government Capital Spending
AI is changing this topic in three practical ways, especially for analysts, consultants, bankers and corporate strategy teams.
- Project monitoring becomes more real-time. Computer vision, drone imagery and satellite analytics can compare physical progress with reported milestones, helping lenders and governments detect delays earlier.
- Tender intelligence becomes faster. AI tools can classify thousands of tenders by geography, sector, buyer, ticket size and eligibility, helping companies decide where to bid.
- Capex-to-sector forecasting improves. Machine learning models can combine budget outlays, tender awards, commodity prices, order books and freight indicators to estimate which sectors may see demand first.
Load a Budget speech, a ministry demand-for-grants document and one company annual report into NotebookLM. Ask: “Map the capex announcements to sectors, identify direct and indirect beneficiaries, and create five interview questions on order book, margins and working capital.” Then verify every number from the original documents before using it.
Interview Relevance
“The government has increased capital spending. Which sectors benefit, and how would you analyse whether the impact is real?”
If the interviewer asks for “sectors,” do not give a list. Give a timed map: immediate, second-order and productivity-led beneficiaries. That sounds much more analytical.
Common Mistake
The biggest mistake is saying “government capex benefits infrastructure” and stopping there. It costs candidates because it ignores timing, working capital, supplier chains and execution risk. The one-line fix: always answer through the chain - outlay - tender - order - execution - cash - sector earnings.