
Value Chain Analysis & Where Profit Pools Sit
A smartphone may sell for a premium, but the factory that assembled it may earn only a thin manufacturing margin. The surprising lesson: the company touching the product is not always the company capturing the profit.
- Value chain analysis breaks a business into activities to see where value is created, cost is incurred and profit is captured.
- Profit pools are the parts of an industry value chain where the economic profits actually sit.
- Do not stop at “manufacturing, marketing, sales.” Ask: who has pricing power, scarce capability, customer access, data, switching costs or regulation-backed control?
- The same industry can have low-margin activities and high-margin activities sitting next to each other.
- A good answer maps the chain, overlays economics, explains power, then recommends where to play or how to move upstream/downstream.
- The trap: assuming revenue pool equals profit pool. Big sales do not automatically mean attractive profit.
Big Picture: Follow the Money, Not Just the Product
Value chain analysis is a way to open the business “black box.” Instead of saying “the company sells electronics” or “the company runs logistics,” you separate the chain into activities and ask which activity creates value, which activity absorbs cost, and which activity captures profit.
If you already understand industry structure, value chain analysis is the natural next layer. Use Competitive Landscape & Barriers to Entry to judge why a profit pool stays protected once you find it.
Core Explanation: How Value Chain Analysis Works
The big idea is simple: every business is a sequence of activities, but not every activity is equally profitable. Some activities are necessary but commoditized. Others control the customer, the data, the brand, the technology or the scarce asset - and therefore capture a larger share of profit.
For example, in consumer electronics, final assembly can be operationally complex but still fiercely competitive. Brand, software ecosystem, design, distribution and after-sales relationship may capture more attractive profit because they influence willingness to pay and customer lock-in.
The 5-Step Process to Locate Profit Pools
Definitions You Can Say in One Breath
- Value chain analysis: breaking a business into activities to see where value is created, cost is incurred and profit is captured.
- Profit pool: the total economic profit earned at different stages of an industry value chain.
- Economic profit: operating profit after charging for the capital required to generate it.
Michael Porter popularised the value chain as a strategy tool in Competitive Advantage, where the firm is analysed as linked activities rather than a single profit machine.
Where Profit Pools Usually Sit
Profit pools generally sit where a player has one or more of six advantages: control over demand, control over supply, proprietary capability, scale economics, regulatory position or switching costs.
When the analysis moves into unit economics, revise Contribution Margin & Break-Even Analysis in Cases so you can quantify whether an activity is genuinely attractive or merely busy.
Metrics: How to Test Whether a Stage Is a Real Profit Pool
There is no universal “good margin” across industries. A grocery retailer, software platform and electronics manufacturer have different economics. So in interviews, use relative benchmarks: compare each activity with the company average, direct competitors and cost of capital.
A company compares two stages. Stage A earns ₹100 revenue, ₹70 variable cost and uses ₹200 capital. Stage B earns ₹60 revenue, ₹20 variable cost and uses ₹50 capital. Stage A contribution is ₹30, but Stage B contribution is ₹40 on lower capital. If operating costs are controlled, Stage B may be the better profit pool despite lower revenue.
Profit Pool Matrix: Attractive vs Defensible
A stage can be profitable today but easy to attack tomorrow. The best profit pools are both attractive and defensible: they generate returns and have barriers that protect those returns.
This is why “where should we play?” is different from “where is the revenue?” A revenue-heavy stage with low margins, high working capital and no differentiation may be a poor strategic choice.
Mini Case Study: Dixon Technologies and the Electronics Value Chain
Dixon shows how an Indian electronics manufacturer can improve its position by moving beyond pure assembly toward capability, scale and deeper customer relationships.
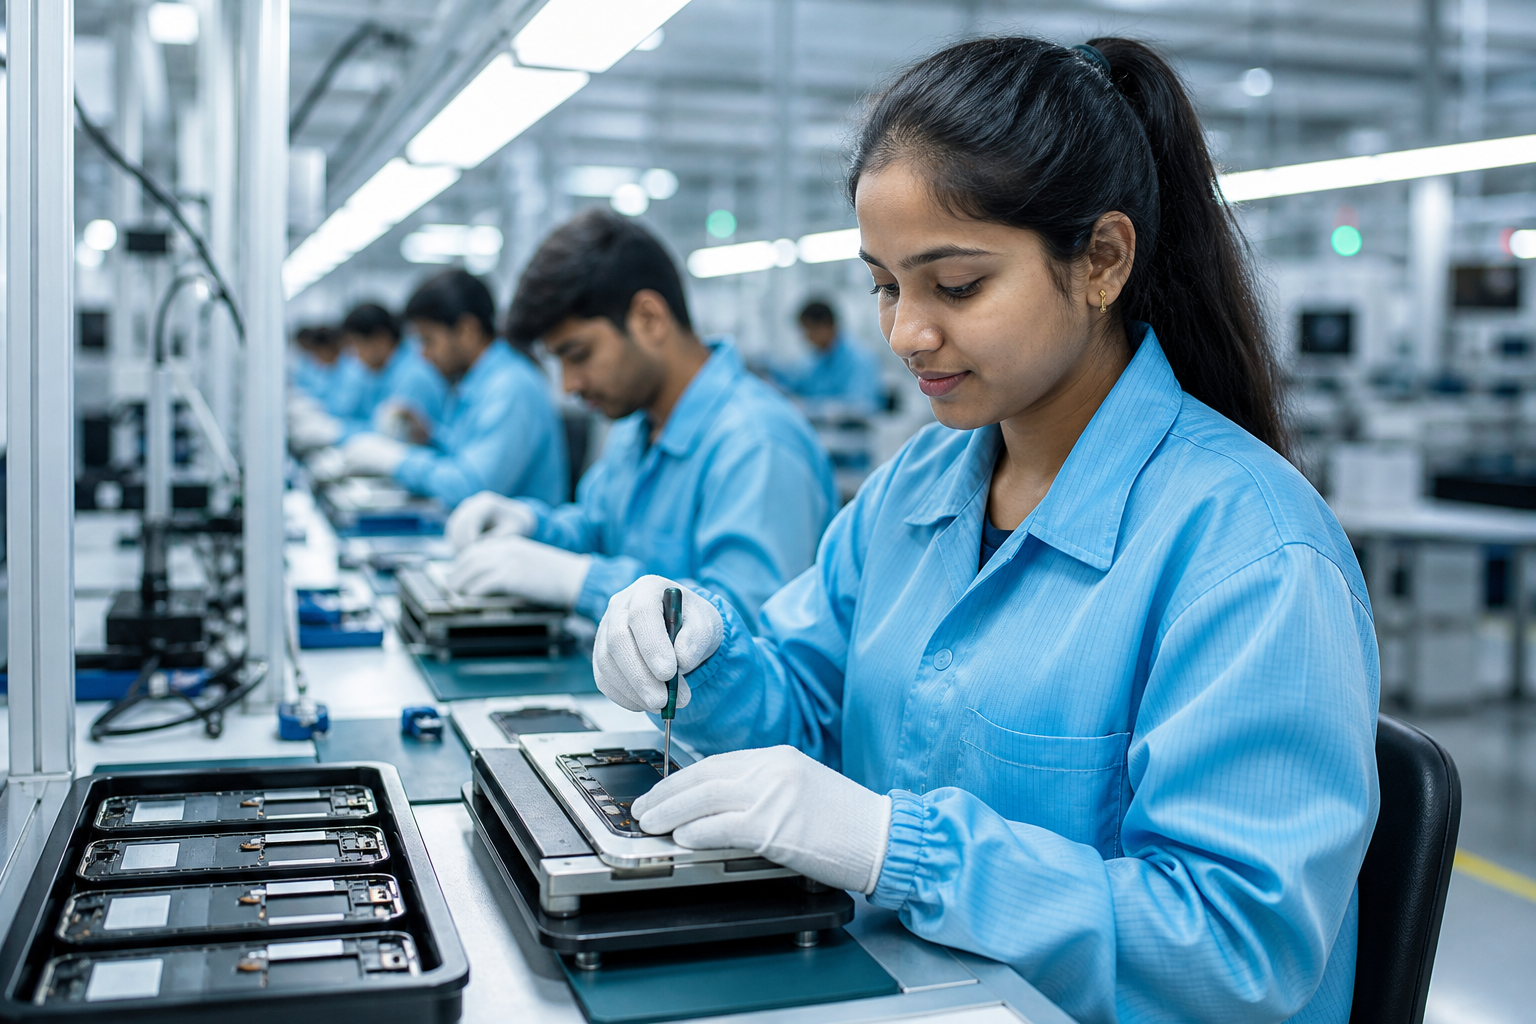
Situation: Electronics brands want speed, quality and flexibility, but building and operating factories is not always their core advantage. Contract manufacturers step in to handle production, quality systems, sourcing coordination and capacity management.
The move: Dixon Technologies built its position around manufacturing execution in India: production capability, process discipline, customer relationships and the ability to serve multiple electronics categories. The strategic logic is not “assembly alone is attractive.” The stronger logic is that assembly becomes more valuable when supported by scale, procurement capability, quality systems, category know-how and potential movement into design-led or deeper manufacturing activities.
Outcome or lesson: The profit pool in electronics is not evenly spread. Pure assembly can be competitive and margin-constrained. Better economics appear when a player adds harder-to-copy capabilities: manufacturing reliability, supplier coordination, design support, speed to market and trusted relationships with brand owners. Dixon’s case teaches that moving along the value chain is often about upgrading the activity, not merely adding more activity.
So what: Dixon is a useful interview example because it prevents a simplistic answer. Manufacturing is not automatically low value, and brand ownership is not automatically sufficient. The primary driver is capability-led manufacturing scale, supported by supplier coordination, quality execution, category breadth and customer stickiness.
How AI Changes Value Chain Analysis & Profit Pools
AI changes value chain analysis by making invisible activity economics more visible. Instead of relying only on management interviews and high-level financials, firms can now analyse transactions, process logs, customer conversations and operational bottlenecks at a more granular level.
- Activity-level cost tracing: AI can classify invoices, tickets, calls and process steps to reveal which customers, products or regions consume disproportionate service cost.
- Demand and pricing intelligence: Machine learning can identify where willingness to pay differs by segment, helping firms locate profit pools in premium SKUs, subscriptions, bundles or after-sales services.
- Operational digital twins: In manufacturing, logistics and retail, AI simulations can test how changes in capacity, routing, inventory or staffing shift margins across the chain.
Use NotebookLM: upload the company annual report, investor presentation and this lesson, then ask: “Map the company’s value chain, identify likely profit pools, list evidence for each, and generate five interview questions.” Use ChatGPT or Claude next to pressure-test whether your profit-pool logic confuses revenue with economic profit.
Interview Relevance
“A company’s revenues are growing but margins are flat. Use value chain analysis to identify where profit pools sit and what the company should do.”
Use the phrase “profit pool, not revenue pool.” It signals that you understand economics, not just market size.
Common Mistake
The most common mistake is mapping activities but not explaining why profit sits in one activity and not another. It costs candidates because the answer becomes descriptive, not strategic. One-line fix: after every activity, ask “what power does this stage control - customer, cost, data, IP, scarcity or regulation?”