
Working Capital, Cash Flow & Funding Constraints
A distributor can show a healthy profit on paper and still panic on Friday because salaries are due, suppliers are calling, and customers will pay only after 60 days. That is the brutal lesson of working capital: growth does not automatically create cash - sometimes it eats cash first.
- Working capital is the cash trapped in day-to-day operations: inventory, receivables and payables.
- Net working capital = current assets - current liabilities. Positive is not always good; too much may mean idle cash or slow collections.
- Cash conversion cycle = DIO + DSO - DPO. It tells you how many days cash is locked before returning.
- A profitable business can fail if receivables grow faster than collections or inventory piles up faster than sales.
- Funding constraint means the business cannot raise enough external cash, so operations must release cash internally.
- The best answer links three layers: P&L profit, balance-sheet working capital, and cash-flow timing.
- Interview fix: quantify the funding gap first, then improve collections, inventory turns, supplier terms and growth pacing.
Big Picture: Profit Is an Opinion, Cash Is a Constraint
Working capital sits between sales and cash. The company may book revenue today, but cash arrives only when the customer pays. Meanwhile, inventory must be bought, staff must be paid, and suppliers may demand money before the customer settles the invoice.
Core Explanation: The Three Questions That Matter
Whenever you see working capital, cash flow and funding constraints together, reduce the problem to three questions:
This is why a high-growth company often needs more cash, not less. If sales rise on credit, receivables rise. If the company stocks ahead of demand, inventory rises. Unless payables or external funding expand at the same pace, the business hits a cash squeeze.
Definitions You Should Be Able to Say in One Breath
- Working capital: Capital tied up in current assets and current liabilities used to run daily operations.
- Net working capital: Current assets minus current liabilities.
- Operating cash flow: Cash generated by core business operations after working-capital movements.
- Free cash flow: Cash left after operating needs and capital expenditure.
- Funding constraint: A limit on how much cash the business can raise from debt, equity or internal accruals.
- Cash conversion cycle: Days inventory is held plus days receivables are outstanding minus days payables are unpaid.
The Working Capital Metrics That Actually Matter
Do not say “we should improve working capital” vaguely. In interviews, name the measure, formula and what a good number means. Always compare with industry norms because grocery retail, SaaS, manufacturing and construction have very different cash cycles.
Worked Example: Estimating the Funding Gap
Suppose a manufacturer has annual COGS of ₹36.5 crore, average inventory of ₹5 crore, average receivables of ₹6 crore, average payables of ₹8 crore, and annual credit sales of ₹36.5 crore.
Now the insight: if customers start paying 20 days later, the cash conversion cycle becomes 50 days, and the business needs roughly ₹2 crore more cash. Nothing changed in the income statement immediately, but the cash problem became real.
Funding Constraints: What Changes When Cash Is Not Freely Available
A funding constraint turns a finance problem into a strategy problem. If the company cannot easily raise debt or equity, it must make trade-offs: slow growth, reduce inventory, collect faster, renegotiate suppliers, cut discretionary spending, or improve unit economics through contribution margin and break-even analysis.
The key is to separate healthy cash release from desperate cash extraction. Reducing obsolete inventory is healthy. Refusing to pay critical suppliers may show cash improvement for one quarter but can break the supply chain later.
Quick-commerce businesses in India illustrate the working-capital tension sharply. Customers pay quickly, but the company must fund dark-store inventory, delivery capacity and availability expectations. The primary driver of cash discipline is fast inventory rotation, supported by demand forecasting, supplier terms, assortment control and store-level contribution economics.
Case Study: DMart and the Working-Capital Discipline Behind Low Prices
DMart shows how a retailer can make working-capital discipline part of the operating model, not just a finance department clean-up exercise.
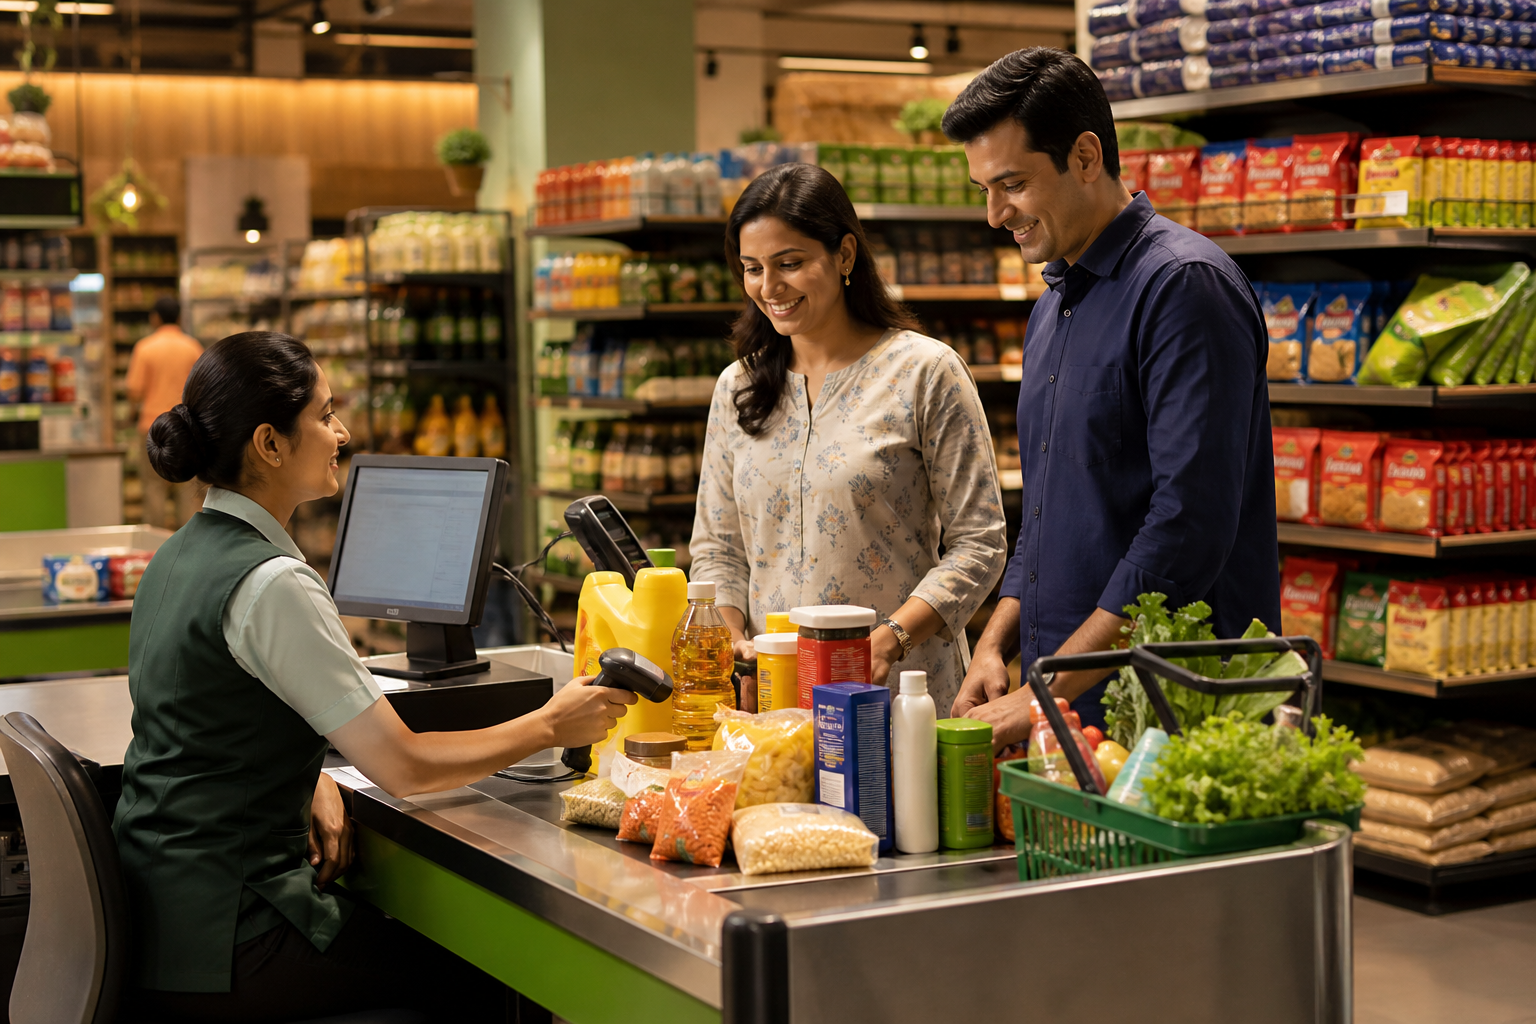
Retail is a tough working-capital business because margins are thin, customers expect availability, and unsold inventory quietly eats cash. DMart’s model is memorable because the cash logic and customer promise reinforce each other: everyday value, disciplined assortment, fast-moving products and tight cost control.
The primary driver is inventory productivity - selling a focused range of high-velocity items rather than locking cash in slow-moving variety. Supporting drivers include disciplined store economics, vendor relationships, operating-cost control and a value proposition that encourages repeat footfall.
The lesson is not “low prices win.” The lesson is that low prices are financially sustainable only when the operating system releases cash quickly enough to fund the promise.
How AI Changes Working Capital, Cash Flow & Funding Constraints
AI is making working-capital management more predictive and less reactive. Instead of discovering a cash squeeze after receivables age or inventory piles up, firms can now forecast pressure points earlier.
Student workflow: Load a company annual report, recent results transcript and your own working-capital notes into NotebookLM. Ask it to produce: “What are the likely working-capital risks, what numbers should I calculate, and what interviewer follow-ups could test my answer?” Then practise the final explanation using AI as a mock interviewer.
Interview Relevance
A profitable B2B manufacturer is growing fast but has maxed out its bank working-capital limit. The CEO says, “Sales are up, so why are we short of cash?” How would you diagnose and solve this?
If the case starts sounding distressed, explicitly say: “I will first quantify the liquidity runway, then separate operational fixes from emergency funding options.” That connects this topic naturally to turnaround and distressed business cases.
Common Mistake
The costly mistake is saying, “The company is profitable, so funding should not be a problem.” Profit is not cash. The one-line fix: always reconcile profit to operating cash flow by showing what happened to inventory, receivables and payables.