
Applied: A Full Automotive & Mobility Teardown
The most revealing part of an electric scooter is not the battery. It is what happens after the sale - financing, charging confidence, service quality, software updates, resale value and whether the rider trusts the brand enough to recommend it.
That is the entire automotive and mobility sector in one scene: the vehicle is the product, but the business is a web of manufacturing, finance, distribution, software, regulation and lifetime ownership economics.
- Do not teardown automotive as “cars and bikes”. Break it into vehicle segments, powertrains, use cases and value pools.
- The core map is: demand - value chain - profit pools - regulation - disruption - company position.
- Automotive is fixed-cost heavy. Scale, capacity utilisation, platform sharing and supplier economics matter as much as consumer demand.
- Mobility changes the unit of analysis. The question shifts from “who sells vehicles?” to “who controls trips, fleets, financing, data and ownership experience?”
- EVs shift value pools. Batteries, software, charging, electronics, aftersales and residual value become central to competition.
- In interviews, win by being structured and peer-relative. Compare segments using the same framework instead of throwing isolated facts.
- The biggest trap: giving a consumer-facing answer while ignoring suppliers, dealers, finance, regulation and aftersales.
Big Picture: A Teardown Is a Profit Pool Map, Not a Company List
A full automotive and mobility teardown answers one question: where is value created, who captures it, and what is changing the capture logic? Start with the customer need, then move through the business system that satisfies it.
This is why a good automotive answer sounds different from a general consumer-goods answer. In FMCG, distribution and brand salience may dominate. In automotive, you must also explain platform investment, dealer working capital, component sourcing, financing, warranty risk, residual value and regulation.
The Core Explanation: How to Tear Down Automotive and Mobility
Think of the sector in six layers. If you can move cleanly through these layers, you can answer almost any automotive or mobility interview question.
The Automotive and Mobility Value Chain
The automotive value chain is not a straight line where the OEM automatically wins. It is a set of interdependent players, and each can gain or lose power as technology changes.
Use this map to avoid shallow statements like “EVs help OEMs because EV demand is rising.” A better answer asks: who owns the battery economics, who controls software, who funds inventory, who services the vehicle, and who owns customer data?
For India, start with the SIAM statistics page for industry sales and production categories, and the VAHAN dashboard for vehicle registration trends. For a disciplined source workflow, revise where to find current sector data and which sources to trust.
Four Business Models You Must Separate
Automotive and mobility interviews become much easier when you separate two axes: what powers the vehicle and how the customer uses it. A petrol scooter sold to an individual, an electric three-wheeler used by a delivery fleet, and a ride-hailing cab are not the same business.
Metrics That Make Your Teardown Sound Professional
Use these metrics as a diagnostic checklist. Automotive benchmarks vary sharply by segment, powertrain and geography, so do not memorise one universal “good number”. In interviews, a strong number is one that is improving over time and better than the closest peer set.
A Small Worked Example: EV Breakeven Logic
Use hypothetical numbers when the interviewer wants to test business sense rather than memory. Suppose an EV scooter sells at an average price of ₹1,50,000. Variable cost per scooter is ₹1,20,000. Gross profit per unit is therefore ₹30,000.
If annual fixed cost for the plant, engineering, corporate team and launch support is ₹300 crore, breakeven units are:
Breakeven units = fixed cost ÷ gross profit per unit = ₹300 crore ÷ ₹30,000 = 1,00,000 scooters.
The insight is more important than the arithmetic: automotive businesses need scale because fixed costs are heavy. But scale alone is not enough - product quality, localisation, channel economics, service readiness and financing access must support it.
Definitions You Should Be Able to Say Cleanly
- Automotive sector: Businesses that design, manufacture, distribute, finance, service and recycle motor vehicles and their components.
- Mobility sector: Businesses that enable movement of people or goods through vehicles, platforms, fleets, infrastructure or services.
- Profit pool: The distribution of economic profit across activities, players or stages within an industry.
- Total cost of ownership: Purchase price plus financing, fuel or energy, maintenance, insurance, downtime and resale impact.
- Porter’s Five Forces: A framework analysing rivalry, buyer power, supplier power, entrants and substitutes; see Harvard Business School’s Five Forces overview.
Case Study: Ather Energy and the EV Two-Wheeler Teardown
Ather Energy shows why an EV two-wheeler business must be analysed as a product-plus-ecosystem play, not just a scooter manufacturing story.
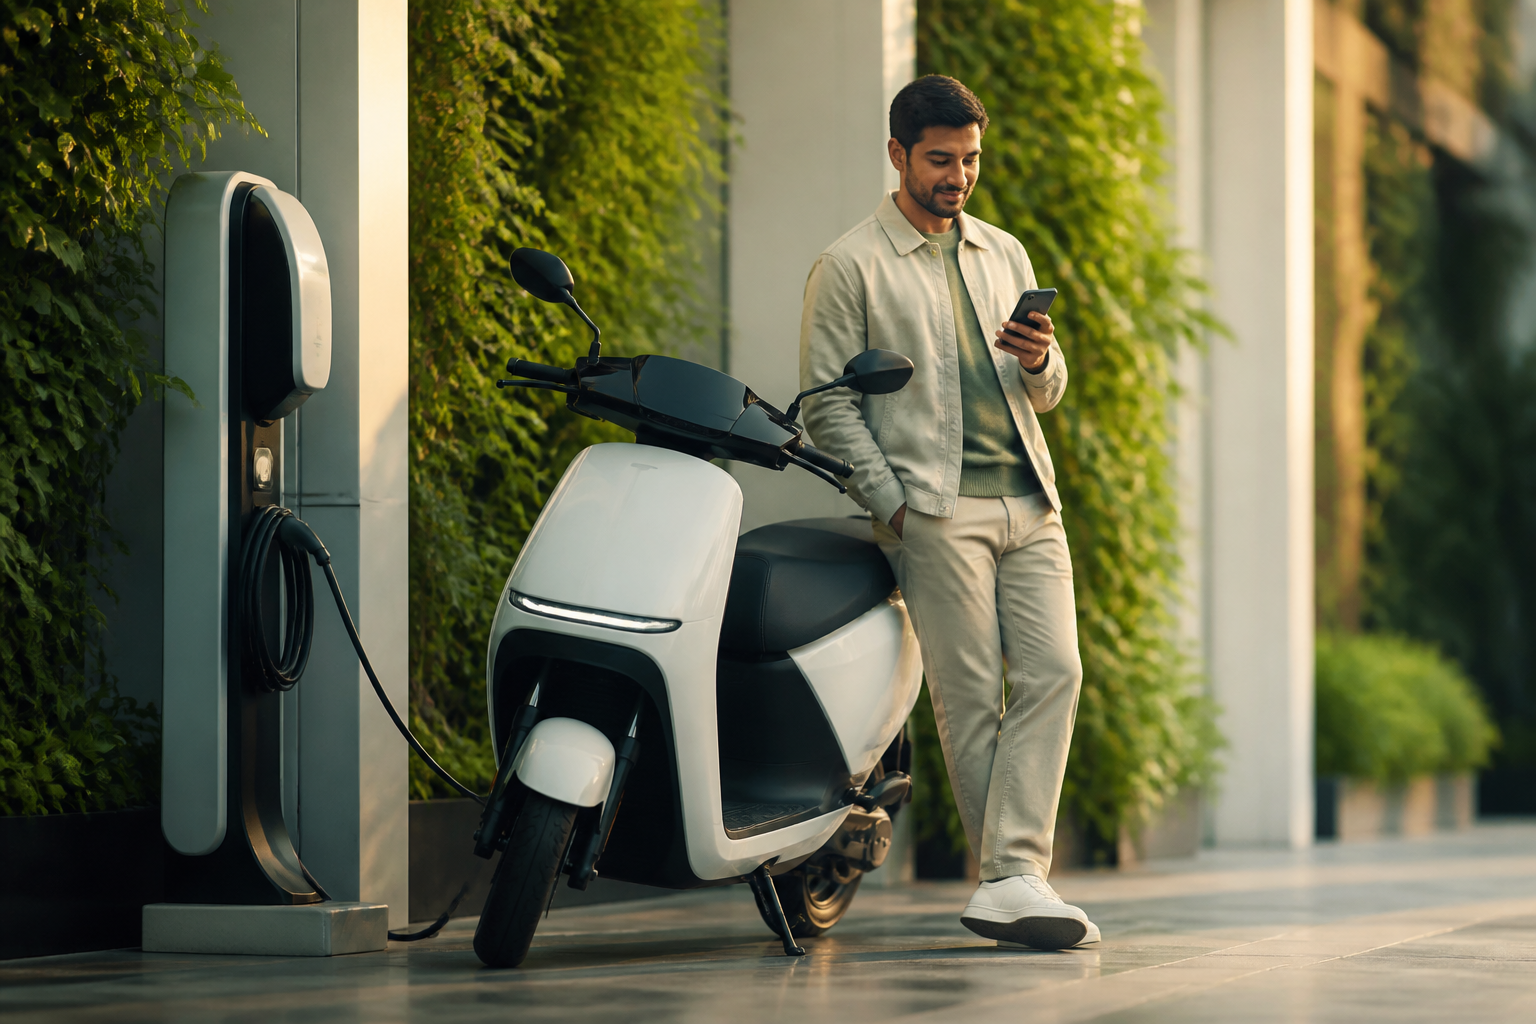
Situation. India’s two-wheeler market is deeply price-sensitive, distribution-led and service-dependent. EV adoption adds a new layer of anxiety: buyers worry about range, charging access, battery life, service capability and resale value.
The move. Ather positioned itself around a more integrated EV ownership experience. The product was only one part of the proposition. The broader system included connected features, charging support, retail experience, service readiness and a premium urban positioning.
Primary driver. The main strategic driver was trust creation in a new category. In early EV adoption, the buyer is not only comparing acceleration or design; the buyer is asking whether the brand reduces uncertainty around daily use.
Supporting drivers. The supporting drivers were software-led user experience, an ecosystem narrative around charging, controlled brand experience, product quality signalling, and a focus on urban customers more willing to pay for technology and reliability.
Outcome and lesson. The lesson is not “premium EVs win because they have better technology.” The sharper lesson is that category creation requires reducing customer risk across the ownership journey. In automotive teardown language, Ather competes across product, software, channel, charging confidence and service - not product alone.
This is the difference between a shallow and a complete answer. A shallow answer says “Ather is an EV scooter company.” A complete answer says “Ather is trying to capture EV two-wheeler value by reducing adoption risk across product, software, charging confidence and service, while competing against scale-rich incumbents.”
How AI Changes Automotive and Mobility
AI is not a generic add-on here. It changes product design, manufacturing, customer experience, fleet economics and finance.
Practical student workflow: use NotebookLM to upload one OEM annual report, SIAM category data, a VAHAN registration snapshot and two competitor investor presentations. Ask it to produce a two-page sector teardown with five sections: demand, value chain, profit pools, regulation and disruption. Then manually verify every number using the original source. If you need a refresher on annual report extraction, revise reading an annual report for sector insight.
Interview Relevance
“Pick one segment in automotive or mobility - say EV two-wheelers, passenger cars, ride-hailing or commercial vehicles - and give me a full sector teardown. Where are the profit pools, and who is best placed to win?”
If the interviewer gives no numbers, say: “I would triangulate using SIAM sales, VAHAN registrations, company annual reports and dealer/channel checks.” For estimation practice, revise sizing a sector when no number exists.
Common Mistake
The mistake that costs candidates is treating automotive as a consumer-brand category only. That misses fixed costs, suppliers, dealers, finance, service, regulation and residual value. One-line fix: always answer through demand, value chain, profit pools, regulation and disruption before naming winners.