
How the Electronics & Semiconductors Value Chain Works
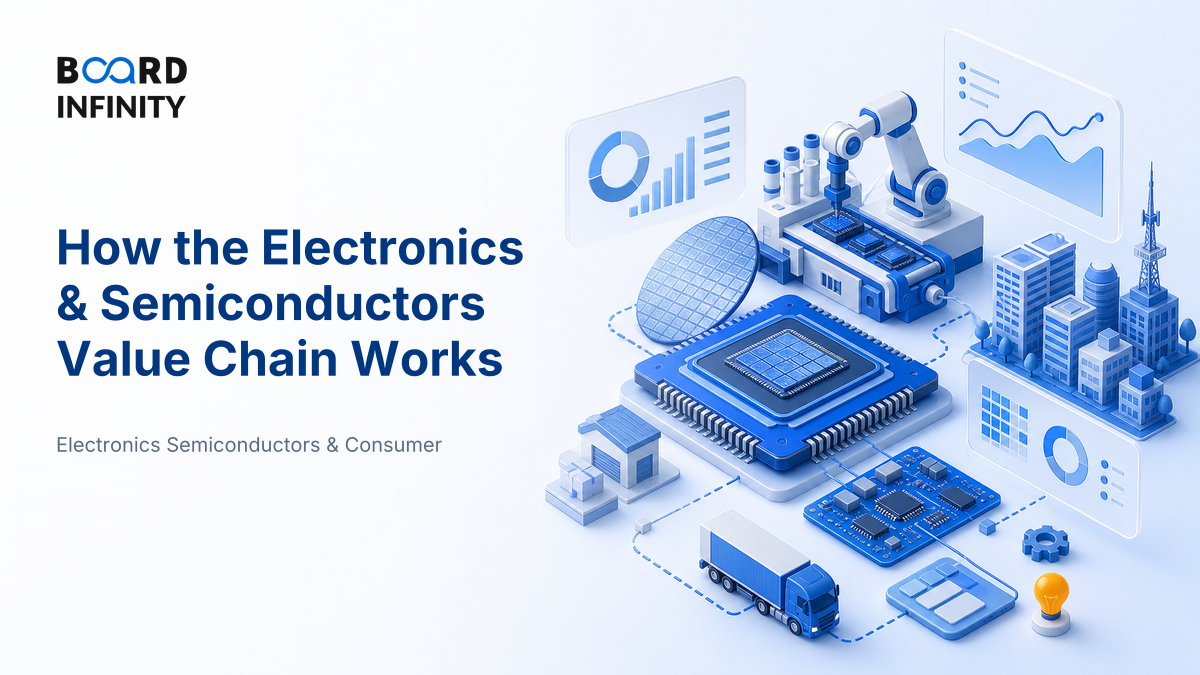
A smartphone on a store shelf looks like one product, but it is really a relay race. The chip may be designed in one country, fabricated in another, packaged and tested somewhere else, assembled into a device by an EMS player, shipped through distributors, and finally sold by a brand that owns the customer relationship.
- Electronics is the finished-device chain: components, boards, assembly, software, distribution, retail and after-sales.
- Semiconductors are the deep upstream chain: chip design, wafer fabrication, packaging, testing and integration into electronics.
- The industry is highly modular: fabless firms design, foundries manufacture wafers, OSATs package and test, and EMS firms assemble products.
- Value and power sit where capabilities are rare: advanced design IP, process technology, yield control, supply assurance, brand access and ecosystem lock-in.
- The common mistake is treating the chain as linear manufacturing. The better answer shows interdependence, bottlenecks and profit pools.
- India is trying to move from electronics assembly toward deeper component, semiconductor, packaging and design participation.
Big Picture: One Device, Two Interlocked Value Chains
Think of electronics and semiconductors as two chains that meet inside the product. The semiconductor chain creates the chips; the electronics chain turns chips, displays, batteries, boards, software and brand experience into a sellable device.
The key interview insight: electronics is closer to the consumer; semiconductors are closer to technology bottlenecks. A phone brand may own the customer, but the chip foundry may control a scarce manufacturing capability. An EMS company may run the factory, but the operating margin may depend on scale, utilization and component sourcing discipline.
Core Explanation: How the Chain Actually Works
The electronics and semiconductor value chain has six practical layers. In interviews, do not memorize company names first. First understand what each layer contributes, what capability is scarce, and how money is made.
The Semiconductor Funnel: Why So Few Ideas Become Working Chips
A semiconductor product moves through a narrowing funnel. Many chip concepts are explored, fewer are designed, still fewer are fabricated successfully, and only a subset wins adoption inside actual products.
This is why semiconductor cycles feel unforgiving. A design miss is expensive. A low-yield manufacturing run hurts economics. A missed customer qualification can delay revenue even if the chip technically works. The best companies manage the funnel by matching product roadmaps, process capability, customer demand and supply commitments.
The Main Business Models in the Chain
Most companies sit in one or two parts of the chain, not all of it. Their economics differ sharply.
A clean answer should distinguish who owns the customer from who owns the bottleneck. In electronics, the brand may capture loyalty. In semiconductors, the bottleneck may be process technology, advanced packaging, specialized tools, IP or design talent.
Definitions You Should Be Able to Say in One Breath
- Value chain: the sequence of activities that turns inputs into a product customers are willing to pay for.
- Semiconductor value chain: the activities that convert chip ideas into designed, fabricated, packaged, tested and usable integrated circuits.
- Electronics value chain: the activities that convert components, software and manufacturing capability into finished devices and after-sales support.
- Fabless company: a chip company that designs semiconductors but outsources wafer manufacturing to foundries.
- Foundry: a manufacturing company that fabricates semiconductor wafers for external chip designers.
- OSAT: outsourced semiconductor assembly and test providers that package chips and test them after wafer fabrication.
- EMS: electronics manufacturing services firms that assemble finished products or sub-systems for brands.
How to Track Whether a Player Is Strong
Do not use one metric across the whole chain. A foundry, an EMS player and a brand have different success logic. Use the metric that matches the business model.
For annual-report practice, use the same logic: first locate which part of the chain the company sits in, then read the relevant margin, utilization, inventory and customer-concentration signals. If you need a general approach, revise reading an annual report for sector insight.
A smartphone brand may earn from product pricing, services and ecosystem loyalty. The processor designer earns from chip design and platform adoption. The foundry earns from wafer manufacturing capacity. The EMS player earns from scaled, reliable assembly. The strategic point: the visible brand is only one node in the value chain; hidden bottlenecks can be just as powerful.
Dixon Technologies: The Full Framework in One Indian Business
Dixon Technologies shows how an Indian EMS player can create value by becoming the manufacturing and execution layer behind multiple electronics categories.
Situation: India’s electronics market has strong demand, but finished devices depend on a complex upstream base - chips, displays, batteries, boards, mechanical parts, software and logistics. Many brands do not want to own every factory capability themselves, especially when demand shifts across categories.
The move: Dixon Technologies built itself as an electronics manufacturing services player. Its core job is not to “own the consumer” like a brand; it is to execute manufacturing programs for brands across categories such as consumer electronics, lighting, home appliances and mobile-related manufacturing. The primary driver is manufacturing execution at scale. Supporting drivers include supplier coordination, quality systems, customer relationships, working-capital discipline and the ability to adapt production lines across product programs.
The lesson: EMS companies win when they reduce complexity for brands. But their economics are different from chip designers or consumer brands: they usually operate with tighter margins, depend heavily on capacity utilization and customer programs, and must control quality failures. A shallow answer says “Dixon manufactures electronics.” A strong answer says “Dixon sits in the EMS layer, monetizing scale, process discipline and customer manufacturing programs while India tries to deepen domestic electronics capability.”
India Angle: Why Assembly Is Only the First Step
India’s electronics ambition is not just to assemble finished products. The strategic challenge is to deepen the chain: more components, more design capability, stronger supplier ecosystems, semiconductor packaging, testing, and eventually more fabrication-linked capabilities.
This matters in interviews because India-specific sector questions often test whether you understand the gap between assembling in India and capturing deeper value in India. To compare this sector with another one structurally, use comparing two sectors on the same framework rather than listing random company names.
How AI Changes Electronics & Semiconductors Value Chains
AI affects this chain in two different ways: it increases demand for advanced chips, and it changes how products are designed, manufactured and serviced.
- AI increases semiconductor demand complexity: AI workloads need accelerators, high-bandwidth memory, advanced packaging, thermal management and reliable power systems. This shifts attention from single chips to complete compute systems.
- AI improves design and verification productivity: chip and electronics teams increasingly use AI-assisted tools for design exploration, verification support, defect detection and simulation triage. The bottleneck does not disappear, but engineering cycles can become faster.
- AI strengthens factory intelligence: EMS, OSAT and fab operations can use machine vision for defect detection, predictive maintenance for equipment, and demand-sensing for production planning.
Use NotebookLM or ChatGPT to build a two-page sector brief: paste this lesson, a company annual report, and two competitor profiles; ask it to map each company to the value-chain layer, revenue drivers, KPIs, risks and likely interview questions. Then verify every factual claim manually. For safe research habits, revise using AI to research a sector without importing its errors.
Interview Relevance
“Explain the electronics and semiconductor value chain. Where does India currently participate, and where can more value be captured?”
If the interviewer names a company, do not panic. First place it in the chain. Then explain how that layer makes money, what its bottleneck is, and which metric proves execution quality.
Common Mistake
The mistake: saying “semiconductor companies manufacture chips” as if every company does the same thing. This costs candidates because it hides the most important strategic point - the industry is specialized across design, fabrication, packaging, assembly and brand ownership. Fix: always answer by first naming the company’s value-chain layer, then its capability bottleneck and revenue logic.