
Telecom & Digital Infrastructure at a Glance: Size, Growth & Structure
You tap “Pay” at a metro station kiosk, the QR code opens instantly, the payment authenticates, and the receipt pings before the train doors close. That two-second moment hides a massive stack - spectrum, towers, fibre, core networks, data centres, cloud, cybersecurity and regulation - all working quietly behind the screen.
- Telecom moves voice, data and signals; digital infrastructure stores, processes, secures and routes the data economy.
- Think of the sector in five layers: device demand, access networks, backhaul, core/cloud, and applications.
- Growth is driven by data consumption, 5G densification, fibre rollout, enterprise cloud adoption, data centres, IoT and AI workloads.
- Structure is asset-heavy and regulated: operators need spectrum, towers, fibre, power, rights of way, licences and long-term capex discipline.
- The best sector answer separates market size, growth drivers, profit pools and regulatory constraints.
- Key metrics include ARPU, churn, capex intensity, tenancy ratio, network utilisation and data-centre occupancy.
- The common trap: treating telecom as only mobile operators, while the real sector includes towercos, fibre, data centres, cloud connectivity and managed services.
Big Picture: Telecom Is the Nervous System, Digital Infrastructure Is the Body
Telecom and digital infrastructure is not one industry sitting in one box. It is a layered system where consumer demand, enterprise cloud use and government connectivity targets pull investment into networks, towers, fibre and data centres.
A strong answer begins by saying: “I would size and analyse this sector as a digital stack, not just as telecom service revenue.” That one sentence immediately sounds more mature than a generic answer on mobile subscribers.
What the Sector Includes
Use this five-layer map whenever you need to explain the structure quickly.
If you are comparing this sector with another industry, use a common template - demand, value chain, players, revenue model, regulation and risks. The same logic is explained in comparing two sectors on the same framework.
Definitions You Can Say in One Breath
Telecommunication: Transmission or reception of information by wire, radio, optical or electromagnetic systems, adapted from the ITU Constitution.
Digital infrastructure: The physical and software-enabled assets that store, move, process and secure digital data.
Telecom operator: A licensed firm that provides communication services using spectrum, fibre, core networks and customer-facing distribution.
Towerco: A company that owns passive tower infrastructure and leases site access to one or more telecom operators.
How to Read Size and Growth Without Getting Lost
The sector looks huge because several “sizes” are mixed together: telecom service revenue, network capex, tower leasing revenue, fibre deployment, data-centre capacity and cloud connectivity. Do not quote one number unless you know exactly what it measures.
For India, start with official sector sources: the Telecom Regulatory Authority of India publishes subscription, traffic and revenue indicators in its TRAI Performance Indicator Reports, while the Department of Telecommunications publishes policy and infrastructure context in its DoT annual reports. For a global lens, the GSMA tracks mobile adoption and mobile-economy trends through its Mobile Economy reports.
If no clean market number is available, build it from drivers: users × usage × price, or sites × tenancy × rentals, or data-centre capacity × occupancy × pricing. For a step-by-step method, revise sizing a sector when no number exists.
The Sector Structure: Who Plays Where
The sector has four broad player groups. The cleanest mental model is asset intensity versus customer proximity.
This is why telecom and digital infrastructure is not a simple “subscriber business.” It is a capital-allocation business, an infrastructure-utilisation business and a regulated-services business at the same time. If regulation is central to your answer, use the checklist in locating the regulator and what it controls to identify which body controls licences, tariffs, spectrum, quality of service and consumer protection.
Key Metrics to Track
Use metrics that reveal both demand and infrastructure economics. In interviews, avoid quoting random sector numbers; explain the formula and what the metric tells you.
One practical shortcut: consumer telecom is judged heavily on ARPU, churn and network quality; infrastructure players are judged more on utilisation, tenancy, occupancy, capex discipline and contract visibility.
Growth Drivers and Constraints
Growth comes from demand, but returns come from disciplined capacity creation. The sector can grow in traffic while profits lag if pricing, capex or regulation work against the operator.
Reliance Jio showed how network investment, device adoption, pricing and content demand can expand data usage together; Reliance discusses its digital services business in its annual reports. The primary driver was an all-IP data network built for scale, supported by affordable data plans, smartphone adoption, distribution reach and a broader digital ecosystem. The strategic so what: telecom growth is not just more SIMs - it is more monetisable data behaviour per user.
Case Study: Indus Towers and the Neutral-Host Infrastructure Model
Indus Towers demonstrates how telecom infrastructure can become a shared, asset-heavy B2B business rather than a consumer telecom brand.
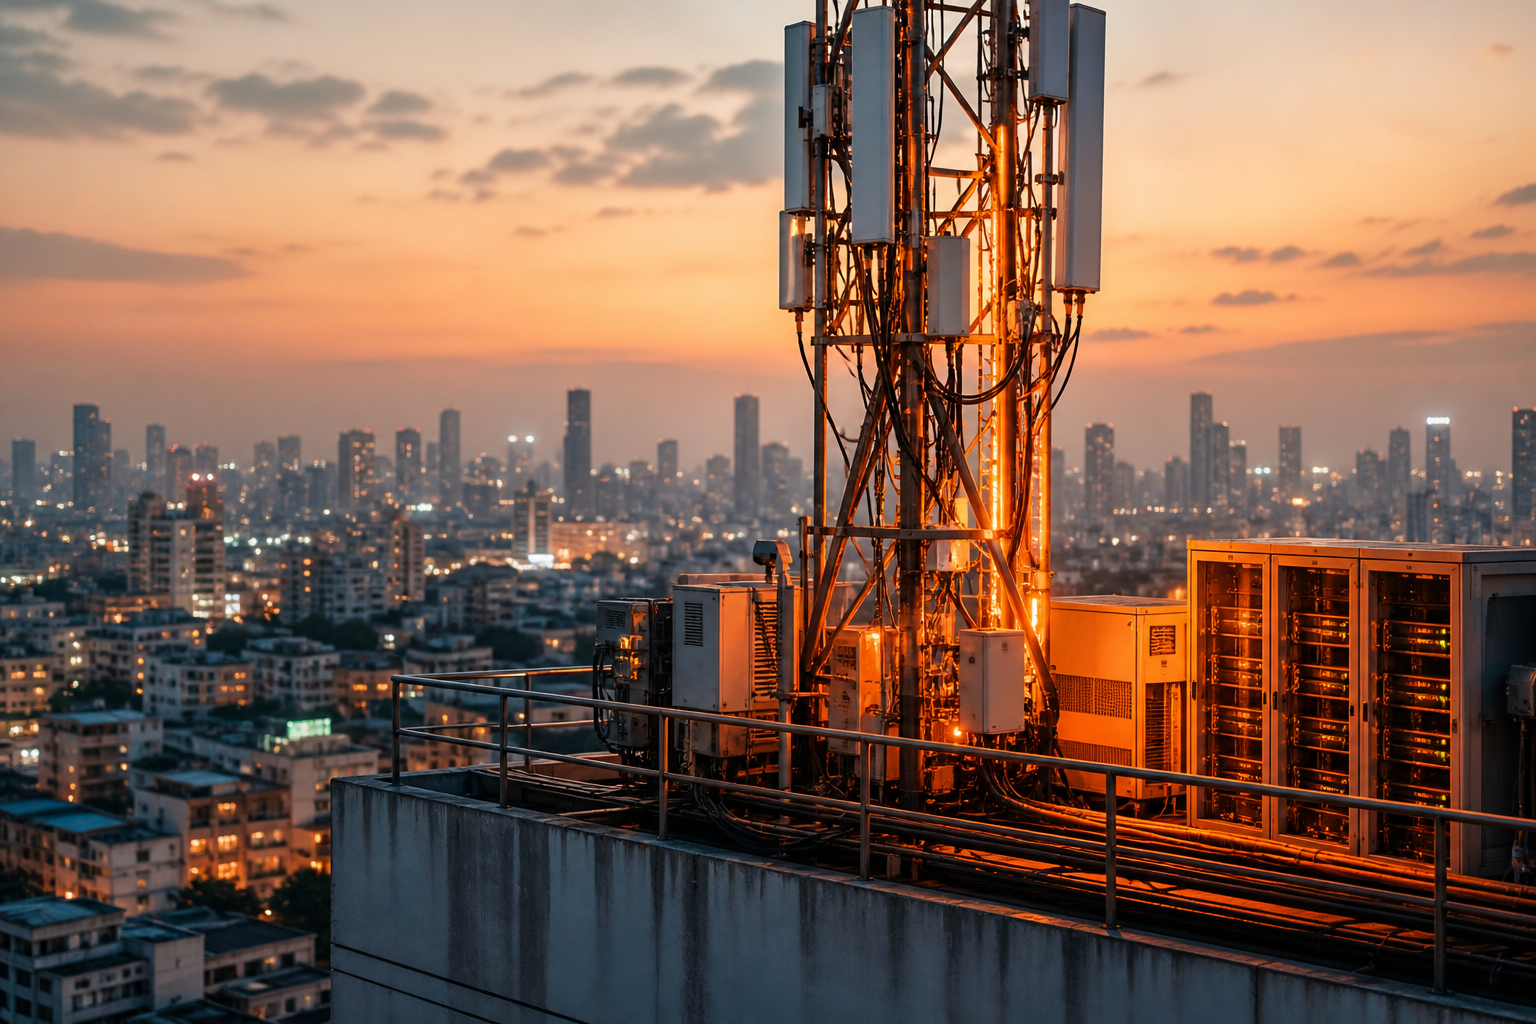
The situation was simple but expensive: every mobile operator needs coverage, capacity, power backup, site access and uptime. If each operator builds a parallel tower network everywhere, the country gets duplicated assets, higher capex and slower rollout.
The move was the towerco model. Indus Towers owns and operates passive telecom infrastructure and leases access to telecom operators; its investor materials describe this tower infrastructure business and its merger history, including the Bharti Infratel and Indus Towers combination completed in 2020 on the Indus Towers annual reports page. Instead of competing for consumers, a towerco competes on site availability, uptime, energy management, rollout speed and the ability to host multiple tenants on the same asset.
The lesson for interviews: Indus Towers is not “just a tower company.” It is a neutral-host infrastructure platform where the business model improves when more tenants use the same physical asset, provided receivables, energy cost and customer concentration are managed well.
How AI Changes Telecom & Digital Infrastructure
AI changes this sector in three concrete ways in 2026.
The caution: AI does not remove physical bottlenecks. A model can recommend a fibre route, but permissions, digging, power, land, spectrum and contracts still decide execution.
Use Perplexity or NotebookLM to load TRAI performance reports, a telecom company annual report and a towerco annual report. Ask: “Separate facts into size, growth drivers, structure, regulation, risks and metrics. Flag any claim that is not supported by the uploaded documents.” For a safer method, revise using AI to research a sector without importing its errors.
Interview Relevance
“Give me a quick overview of the telecom and digital infrastructure sector in India. What is driving growth, and where are the profit pools?”
If the interviewer asks for size, first ask: “Are we sizing telecom services revenue, mobile subscribers, tower infrastructure, fibre, or data-centre capacity?” That clarification signals consulting-style thinking.
Common Mistake
The costly mistake is saying “telecom is growing because everyone uses more internet” and stopping there. That is demand, not structure. Fix it in one line: “More data creates value only when it improves ARPU, utilisation, tenancy, occupancy or enterprise revenue faster than capex and operating cost rise.”