
How the Telecom & Digital Infrastructure Value Chain Works
Most people think telecom is “mobile operators selling SIM cards.” That is like calling an airport “a runway” - the real system includes towers, fibre, spectrum, routers, data centres, cloud platforms, regulators, device makers and content players all working in sequence.
The value chain matters because the company closest to the customer is not always the company capturing the best economics. In telecom and digital infrastructure, profit often sits where scarce assets, high utilisation and long-term contracts meet.
- Telecom is a layered value chain: devices and apps generate demand; networks move data; infrastructure assets provide capacity; operators package service.
- Digital infrastructure includes towers, fibre, data centres, cloud, edge sites, subsea cables and internet exchanges - the physical base of the digital economy.
- The core economics are utilisation-led: the same tower, fibre route or data centre becomes more profitable as more tenants or traffic use it.
- Telecom operators monetise customers; tower companies, fibre owners and data centres monetise capacity, tenancy, uptime and contracts.
- Regulation is not peripheral: spectrum, licences, right-of-way, data governance and quality of service shape who can operate and how they make money.
- Best interview answer: map the layers, identify who pays whom, name the key metrics, then explain one real company example.
- Common trap: discussing only Jio/Airtel/Vodafone Idea and ignoring passive infrastructure, backhaul, cloud and enterprise connectivity.
Big Picture: The Chain That Moves a Byte
A video call, payment, OTT stream or enterprise cloud workload does not “travel through the internet” in one jump. It moves across a stack of assets - some owned by telecom operators, some by independent infrastructure players, and some by cloud or content companies.
The simplest mental model: traffic creates demand, infrastructure creates capacity, operators create service, and customers create revenue.
Core Explanation: The Five Layers of the Value Chain
Use this five-layer structure whenever you need to explain the sector cleanly. It prevents the common mistake of treating telecom as one monolithic business.
Who Does What in the Chain
The value chain becomes easier when you separate asset owners from service packagers. A telecom operator may own some assets, lease others, and partner for the rest.
If you are weak on how to identify the relevant regulator and its control points, revise locating the regulator and what it controls before attempting sector interview answers.
The Economic Flywheel: Why Capacity Keeps Expanding
Telecom and digital infrastructure is not built once. It is a loop. More users and richer applications create more traffic; traffic strains networks; operators and infrastructure firms invest; better networks enable more usage; the loop restarts.
This loop explains why telecom is capital-intensive. It also explains why infrastructure specialists exist: a tower company or data centre firm can focus on asset utilisation while the operator focuses on customer acquisition, pricing and service bundles.
Netflix Open Connect places content delivery infrastructure closer to internet service providers and users. The primary driver is lower delivery friction for heavy video traffic, supported by caching, network partnerships and better local delivery economics. The strategic point: digital demand reshapes telecom infrastructure because popular applications change where capacity is needed.
How Value Is Captured: Scarcity, Scale and Utilisation
Different players capture value for different reasons. The interviewer is testing whether you can see the economics beneath the technology.
Passive infrastructure players win through occupancy and uptime. Telecom operators win through subscriber scale, spectrum efficiency, pricing and churn control. Data centre players win through power availability, location, interconnection density and enterprise contracts. Cloud and content players win through software, ecosystem lock-in and demand aggregation.
Key Metrics to Track
Use metrics to sound commercially sharp. Do not dump technical jargon; connect each metric to the business model.
Worked example: suppose a tower company has 10,000 towers and 18,000 tenant colocations. Its tenancy ratio is 18,000 / 10,000 = 1.8x. If it adds 2,000 colocations without building new towers, the ratio becomes 20,000 / 10,000 = 2.0x. That is powerful because revenue rises while much of the physical site cost is already in place.
Definitions You Can Say in One Breath
- Telecom value chain: The sequence of assets and services that create, carry, process and monetise communication traffic.
- Digital infrastructure: The physical and network infrastructure that enables digital services, including towers, fibre, data centres, cloud and edge sites.
- Backhaul: The network link that carries traffic from access points like towers to the core network.
- Neutral host: An infrastructure owner that serves multiple operators on shared assets instead of serving only one operator.
- Edge computing: Processing data closer to users or devices to reduce latency and improve responsiveness.
Case Study: Indus Towers and the Shared Infrastructure Logic
Indus Towers shows how passive telecom infrastructure can become a specialised business built on tenancy, uptime and long-term operator relationships.
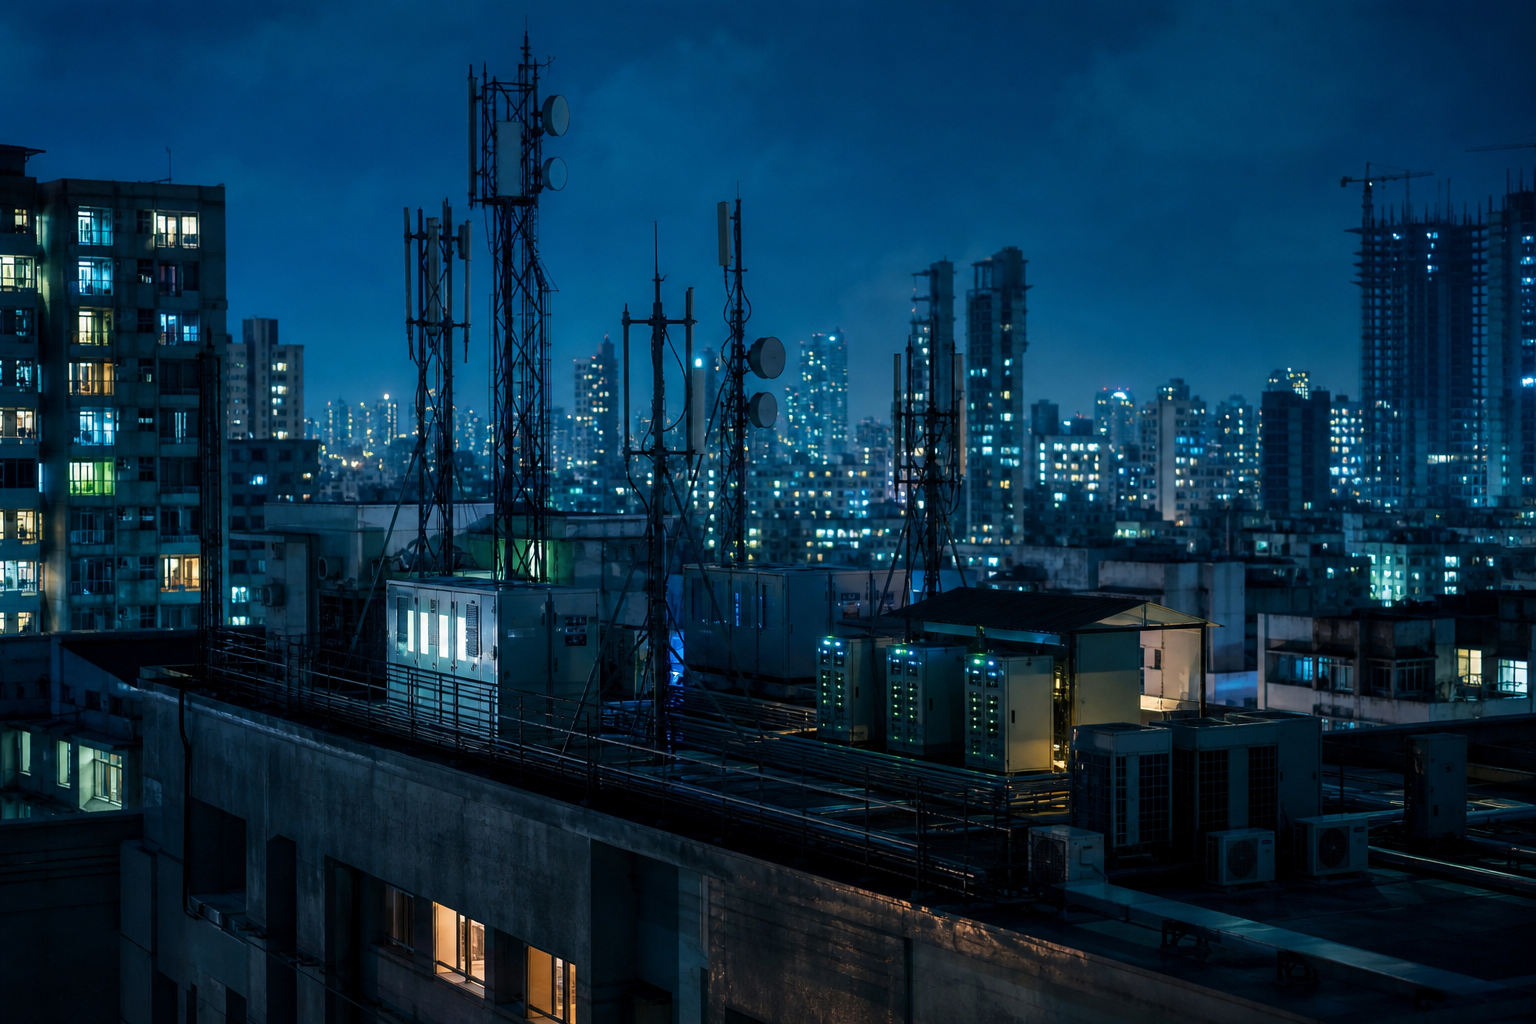
Situation: Mobile data demand in India has kept rising as smartphones, video, payments, work apps and online services became everyday habits. Operators needed broader coverage and denser capacity, but owning every tower site independently would duplicate assets and increase fixed costs.
The move: Indus Towers operates as a passive infrastructure provider. Instead of selling mobile plans to consumers, it provides tower sites, power, physical infrastructure and related operations to telecom operators. Its primary driver is shared asset utilisation: the same site becomes more economically attractive when multiple tenants use it. Supporting drivers include operational uptime, energy management, site acquisition capability, long-term contracts and geographic presence. The company describes its business and investor information on its Indus Towers annual reports page.
Outcome and lesson: The case shows why telecom value is not captured only by the brand whose SIM card the customer uses. In capital-heavy sectors, specialised infrastructure players can create value by improving utilisation, standardising operations and lowering duplication across the ecosystem.
How AI Changes Telecom & Digital Infrastructure
AI does not replace the value chain. It makes each layer more predictive, automated and utilisation-driven.
- AI-led network planning: Operators can forecast traffic by location, time and application type, then decide where to add towers, fibre capacity, small cells or spectrum resources.
- Predictive operations: Tower, fibre and data centre operators can use AI models to predict equipment faults, battery issues, cooling inefficiency or likely outage points before service is hit.
- Smarter enterprise infrastructure: AI workloads increase demand for data centres, high-capacity fibre, low-latency networks and specialised cloud connectivity.
Use Perplexity or ChatGPT to build a player map, but verify every company role from annual reports. A good prompt: “Map the telecom and digital infrastructure value chain in India into access, transport, tower, fibre, data centre, cloud and service layers. For each company, state what it owns and how it earns.” Then cross-check the answer using annual reports for sector insight and this guide on using AI to research a sector without importing its errors.
Interview Relevance
“Walk me through the telecom and digital infrastructure value chain. Where does a tower company or data centre player fit compared with a telecom operator?”
If the interviewer names a company, classify it first: operator, tower company, fibre provider, data centre, cloud, equipment vendor or OTT platform. Then discuss its revenue logic.
Common Mistake
The mistake: treating the sector as “telecom operators sell data packs.” This costs candidates because it ignores the infrastructure businesses that often drive capex, contracts and strategic control. One-line fix: always answer as “asset layer - payer - metric - example.”