
Business Models: How Telecom & Digital Infrastructure Players Make Money
A mobile tower on a highway does not care whether a teenager streams cricket highlights, a kirana store accepts UPI, or a bank verifies a customer through OTP - but every one of those actions depends on it. The tension in telecom and digital infrastructure is simple: huge upfront capital goes in before revenue appears, and the winner is the player who converts capacity into repeatable cash flow.
- Telecom operators make money by selling connectivity - mobile plans, broadband, enterprise links, roaming, IoT and value-added services.
- Digital infrastructure players make money by leasing capacity - towers, fibre routes, data centre space, cloud connectivity and managed infrastructure.
- The sector is a capital-heavy annuity business: high capex first, then recurring revenue if utilization and retention stay healthy.
- The core economic equation is: more traffic is good only when revenue per unit and network cost are under control.
- Telecom is not one business model - it is a stack: consumer connectivity, enterprise solutions, passive infrastructure, data centres and edge networks.
- Track ARPU, churn, utilization, tenancy ratio, EBITDA margin and capex intensity to judge performance.
- The biggest interview mistake is discussing only mobile subscribers and ignoring infrastructure monetization, regulation and capital intensity.
Big Picture: Telecom Is a Layered Money Stack
Do not think of telecom as only SIM cards and recharge packs. Think of it as a layered infrastructure stack: physical assets at the bottom, connectivity in the middle, and digital services at the top. Each layer has a different customer, revenue model, margin profile and risk.
Core Explanation: How These Players Actually Make Money
The cleanest way to understand the sector is to separate who owns the customer relationship from who owns the infrastructure. A mobile operator may do both. A tower company may own only passive infrastructure. A data centre may lease highly reliable space, power and cooling to enterprises and cloud platforms.
1. Telecom Operators: Monetizing Customers and Usage
Telecom operators earn from recurring access to networks. Their revenue is typically a mix of prepaid mobile plans, postpaid plans, fixed broadband, enterprise connectivity, roaming, leased lines, IoT connections and bundled digital services.
The model looks simple - sell plans to customers - but the economics are tougher. Operators must buy spectrum, build radio networks, expand fibre backhaul, pay network operating costs and keep customers from switching. The business works when average revenue per user rises faster than network cost per user.
2. Tower Companies: Monetizing Shared Passive Infrastructure
Tower companies earn by leasing tower space, power support and related passive infrastructure to telecom operators. Their customer is usually not the mobile subscriber; it is the operator that needs coverage without owning every physical site.
The magic word here is tenancy. If one tower hosts one operator, economics may be thin. If the same tower hosts multiple operators, revenue rises while many site-level costs are shared. This is why tower businesses are closer to real estate plus infrastructure operations than to consumer telecom.
3. Fibre and Backhaul Players: Monetizing High-Capacity Routes
Fibre players earn by selling capacity or long-term access on fibre networks. They serve mobile operators, internet service providers, enterprises, data centres, cloud providers and government networks.
Fibre is the hidden engine behind mobile data. A 5G radio site may be visible, but the traffic eventually needs high-capacity backhaul. Fibre economics improve when routes are dense, ducts are reusable, rights-of-way are managed well and multiple customers use the same route.
4. Data Centres: Monetizing Reliability, Power and Location
Data centres earn through colocation, managed hosting, cloud connectivity, interconnection, power usage and value-added services. Customers pay not just for space, but for uptime, cooling, power density, security and proximity to networks.
This makes data centres a bridge between telecom infrastructure and cloud computing. A hyperscale data centre may serve cloud platforms; an edge data centre may sit closer to users to reduce latency for streaming, gaming, fintech, AI inference or enterprise applications.
5. Enterprise Digital Infrastructure: Monetizing Solutions, Not Just Bandwidth
Enterprise telecom revenue comes from private networks, SD-WAN, cybersecurity, cloud connectivity, IoT, managed Wi-Fi, collaboration tools and service-level agreements. Here the customer buys outcomes - reliability, security, monitoring and support - not only data capacity.
For interview answers, this distinction matters. Consumer telecom is usually scale and ARPU-led. Enterprise telecom is account-led, solution-led and SLA-led.
Definitions You Can Say in One Breath
Business model: “A business model describes the rationale of how an organization creates, delivers, and captures value” - Alexander Osterwalder and Yves Pigneur, Business Model Generation.
The Revenue Models: Who Pays, For What, and Why
Use this table to quickly classify any company in the sector. In interviews, classification is half the answer; economics becomes easier once you identify the model.
Metrics That Reveal Whether the Model Is Working
Telecom and digital infrastructure businesses can look impressive at the revenue line but weak underneath. Always ask: is the company increasing monetization, retaining customers, using assets better and funding capex sustainably?
For deeper sector preparation, learn to pull these from filings using annual report analysis for sector insight. If a number is not available, do not invent it - frame the driver qualitatively and compare directionally.
Worked Example: Why One Extra Tenant Changes a Tower Business
Assume a tower site has fixed monthly site costs of ₹100 and can host multiple operators. One operator pays ₹130 per month. A second operator pays ₹90 per month because some site costs are already covered.
This is a simplified illustration, not an industry benchmark. The interview takeaway is precise: tower companies do not need every consumer to pay them; they need operators to share sites efficiently.
Mini Case Study: Indus Towers and the Shared Infrastructure Model
Indus Towers demonstrates how telecom infrastructure can be monetized as a shared, recurring, B2B asset rather than a direct consumer service.
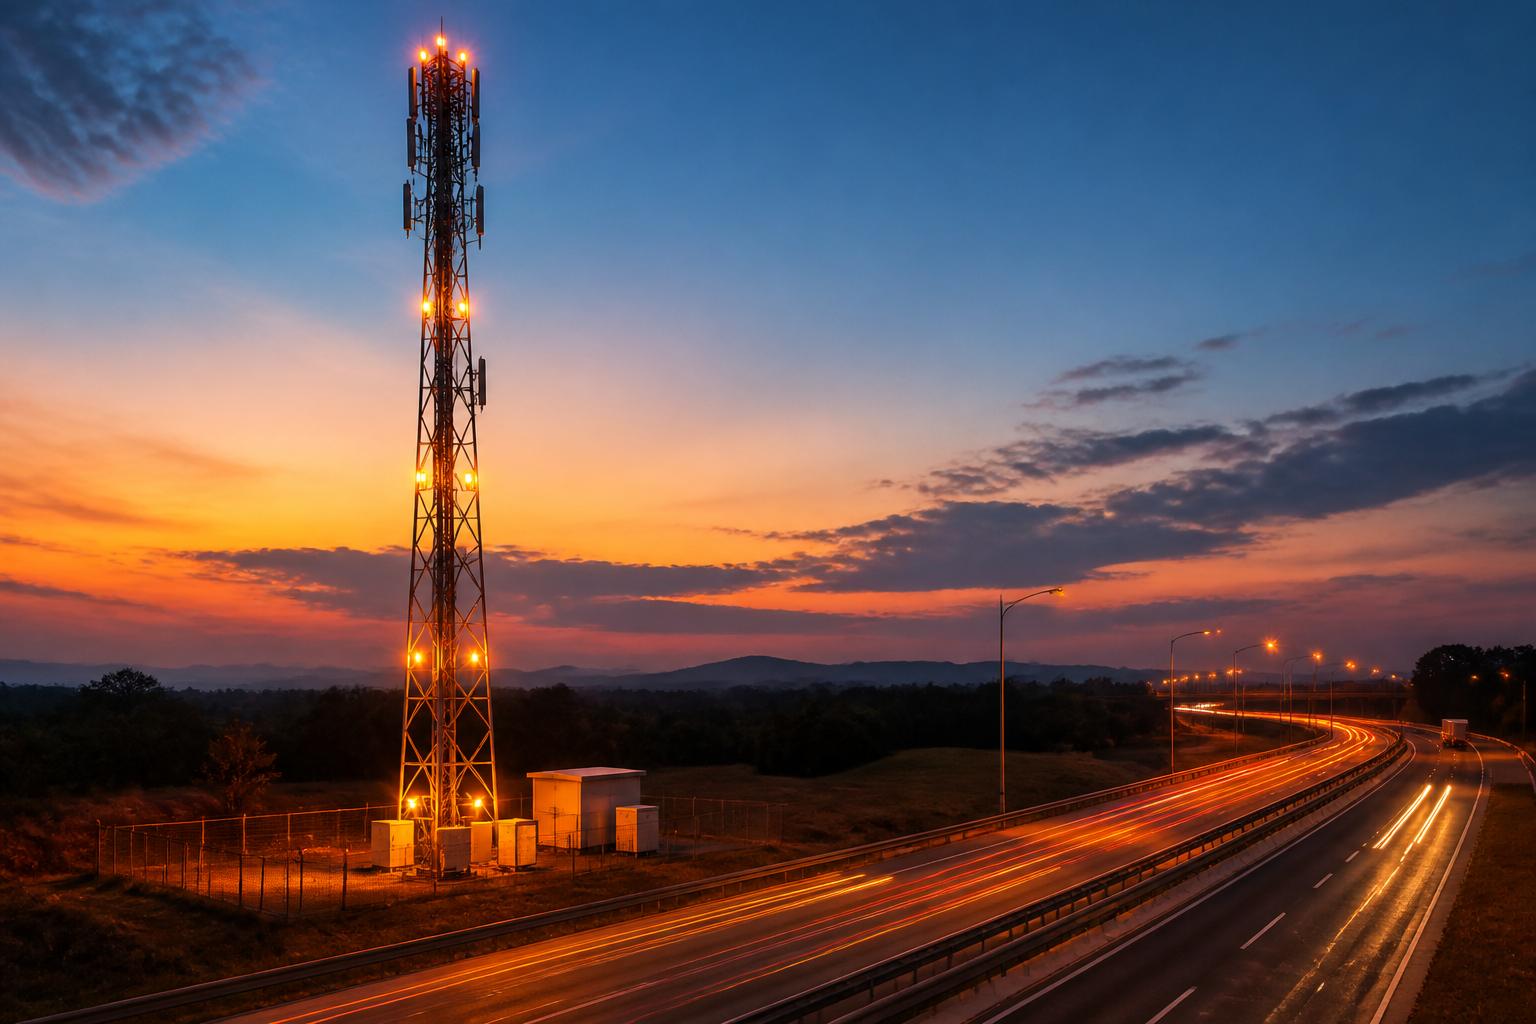
Indus Towers describes itself as a provider of passive telecom infrastructure to mobile network operators in India (Indus Towers). Its business is not to sell mobile plans to consumers. Its business is to provide tower sites and related passive infrastructure that operators can use to expand coverage and capacity.
Situation: India’s mobile data demand created pressure on operators to expand network coverage quickly, but owning every tower site individually would lock up capital and duplicate infrastructure.
The move: The tower company model separates passive infrastructure from active telecom services. Operators can lease space on shared sites, while the tower company focuses on site acquisition, uptime, power management, maintenance and multi-tenant monetization.
Why it works: The primary driver is asset sharing - one tower site can serve multiple operators. Supporting drivers include long-term B2B relationships, site-level operating discipline, scale in maintenance, and demand created by rising mobile data usage.
Lesson: Indus Towers is a reminder that the most important money in digital infrastructure is often not visible to the end user. The consumer sees signal bars; the business model sees tenancy, uptime, energy cost and contracted infrastructure revenue.
How AI Changes Telecom and Digital Infrastructure
AI is changing this sector in operational ways, not just as a buzzword. The strongest use cases sit where networks produce huge volumes of operational data.
- Network planning and optimization: AI models can help forecast traffic hotspots, suggest capacity upgrades and tune networks based on congestion patterns, device density and customer experience signals.
- Predictive maintenance: Tower companies, fibre operators and data centres can use sensor data to predict equipment failures, energy anomalies, cooling issues or site downtime before customers are affected.
- Customer and revenue management: Operators can use AI for churn prediction, personalized recharge offers, fraud detection, enterprise ticket triage and call-centre automation.
Use NotebookLM like a sector analyst: upload one telecom company annual report, one competitor annual report and your notes, then ask, “Compare their business models, revenue drivers, capex priorities and top three interview questions.” Cross-check every generated claim against the uploaded documents.
Use AI carefully. It may confuse telecom operators, tower companies and data centres because all sit in the same ecosystem. If you are using AI for sector research, revise how to research a sector with AI without importing its errors.
Interview Relevance
“How do telecom and digital infrastructure companies make money, and how would you compare a mobile operator with a tower company?”
If the interviewer names a company, classify it first. For example: “This is primarily a tower infrastructure business, so I would judge it by tenancy, uptime, energy cost and contract stability - not by consumer ARPU.”
Common Mistake
Treating telecom as only a subscriber business. This costs candidates because it ignores towers, fibre, data centres, enterprise connectivity, regulation and capex discipline. Fix: answer through the stack - customer revenue at the top, shared infrastructure economics underneath.