
Cost to Serve Analysis by Customer and Region
A sales dashboard can make every region look healthy until the logistics bill arrives. The uncomfortable truth is that two customers with the same revenue can create completely different profit - one orders full truckloads predictably, the other orders small lots, demands urgent delivery, returns often and consumes service time.
- Cost to serve reveals the true cost of fulfilling and supporting a customer, channel, SKU or region after the sale is booked.
- It goes beyond product margin by adding freight, warehousing, order processing, credit, returns, service calls and special handling.
- The output is usually a profitability view: which customers or regions are profit engines, which are value traps, and which need service redesign.
- Use activity drivers - orders, lines, kilograms, kilometres, pallets, visits, returns - instead of blunt revenue-based allocation.
- The best decisions are not always “drop the customer”; often they are minimum order quantity, delivery frequency, pricing, channel migration or network redesign.
- For interviews, structure your answer as: define objective, map activities, assign cost drivers, calculate profitability, segment actions, monitor KPIs.
Big Picture: Revenue Is Not Profit Until Service Cost Is Removed
Cost to serve analysis answers one practical question: after we deliver, support and collect from this customer or region, how much profit is really left? It is especially powerful in FMCG, e-commerce, distribution, logistics, B2B manufacturing and retail because service complexity often hides below the gross margin line.
Core Explanation: What Cost to Serve Actually Measures
Cost to serve analysis measures the total cost of activities needed to sell, fulfil, deliver, service and collect from a customer, channel or region. The key word is activities. The analysis is not asking “who bought the most?” It is asking “who consumed the most resources to generate that revenue?”
Typical service-cost buckets include order processing, picking and packing, warehousing, primary freight, last-mile delivery, sales visits, claims, returns, credit control, special packaging, expedited shipments and customer support. A large customer can still be unattractive if it creates high complexity, frequent exceptions or poor payment behaviour.
The Cost-to-Serve Ladder: From Blunt Allocation to Actionable Profit
A weak cost-to-serve model allocates logistics cost by revenue and calls it analysis. A strong model traces costs to the drivers that actually create them. For example, warehouse picking cost is driven more by order lines than by invoice value; delivery cost is driven by drop density, distance and vehicle utilisation; customer support cost is driven by complaints, claims and manual interventions.
Key Measures: What to Track in a Cost-to-Serve Model
These are the measures an interviewer expects you to name. The “good” number is usually not a universal benchmark; it must be compared within the same business model, category and service promise.
Notice the balance: do not only track cost. Track service outcomes too. A company can reduce delivery cost by shipping late, but that destroys the customer promise. Good cost-to-serve work connects cost with service quality.
Worked Example: Same Revenue, Different Profit
Here is a simple hypothetical example. Assume two customers each generate ₹10,00,000 in net revenue and have the same product cost of ₹7,00,000. On gross margin, both look identical. The difference appears only after service cost is traced.
The decision is not automatically to fire Customer B. The better answer is to diagnose the drivers: small order size, frequent urgent deliveries, high claims or low drop density. Then change minimum order quantities, delivery days, pricing, packaging, credit terms or channel route.
Customer and Region Segmentation: What to Do After the Numbers
Cost to serve becomes useful only when it leads to differentiated action. A profitable customer in a low-density region may deserve protection. A high-revenue but low-profit customer may need a service reset. A strategically important but currently unprofitable region may require network optimisation, not panic.
For region-level analysis, the major drivers are usually distance from plants or warehouses, demand density, vehicle utilisation, return flows, tax or regulatory friction, service promise and channel mix. If the analysis points to structural network issues, the natural next step is network optimisation modelling. If it points to excess inventory positioning, revisit setting inventory policy for a multi-product business because safety stock and replenishment rules often create hidden regional cost.
In an Indian consumer business, a metro customer cluster may be cheaper to serve because drops are dense, replenishment is frequent and returns can be consolidated. A scattered semi-urban region may have the same sales value but higher kilometres per drop, poorer backhaul utilisation and more distributor handling. The strategic lesson: India’s geographic diversity makes regional profitability a logistics question, not just a sales question.
Definitions You Can Say in One Breath
- Cost to serve: Total direct and activity-based cost required to fulfil and support a customer, order, channel or region.
- Activity-based costing: A costing method that assigns costs to outputs based on the activities and resources they consume.
- Cost driver: A measurable activity factor that causes cost to rise or fall, such as orders, kilometres, pallets or returns.
- Customer profitability: Net revenue from a customer minus product cost and the cost of serving that customer.
- Drop density: The number of delivery stops or units served within a route, area or time window.
Wakefit: Cost to Serve in a Bulky D2C Business
Wakefit shows why customer and region profitability matter when a business sells bulky products that are expensive to store, move, deliver and sometimes return.
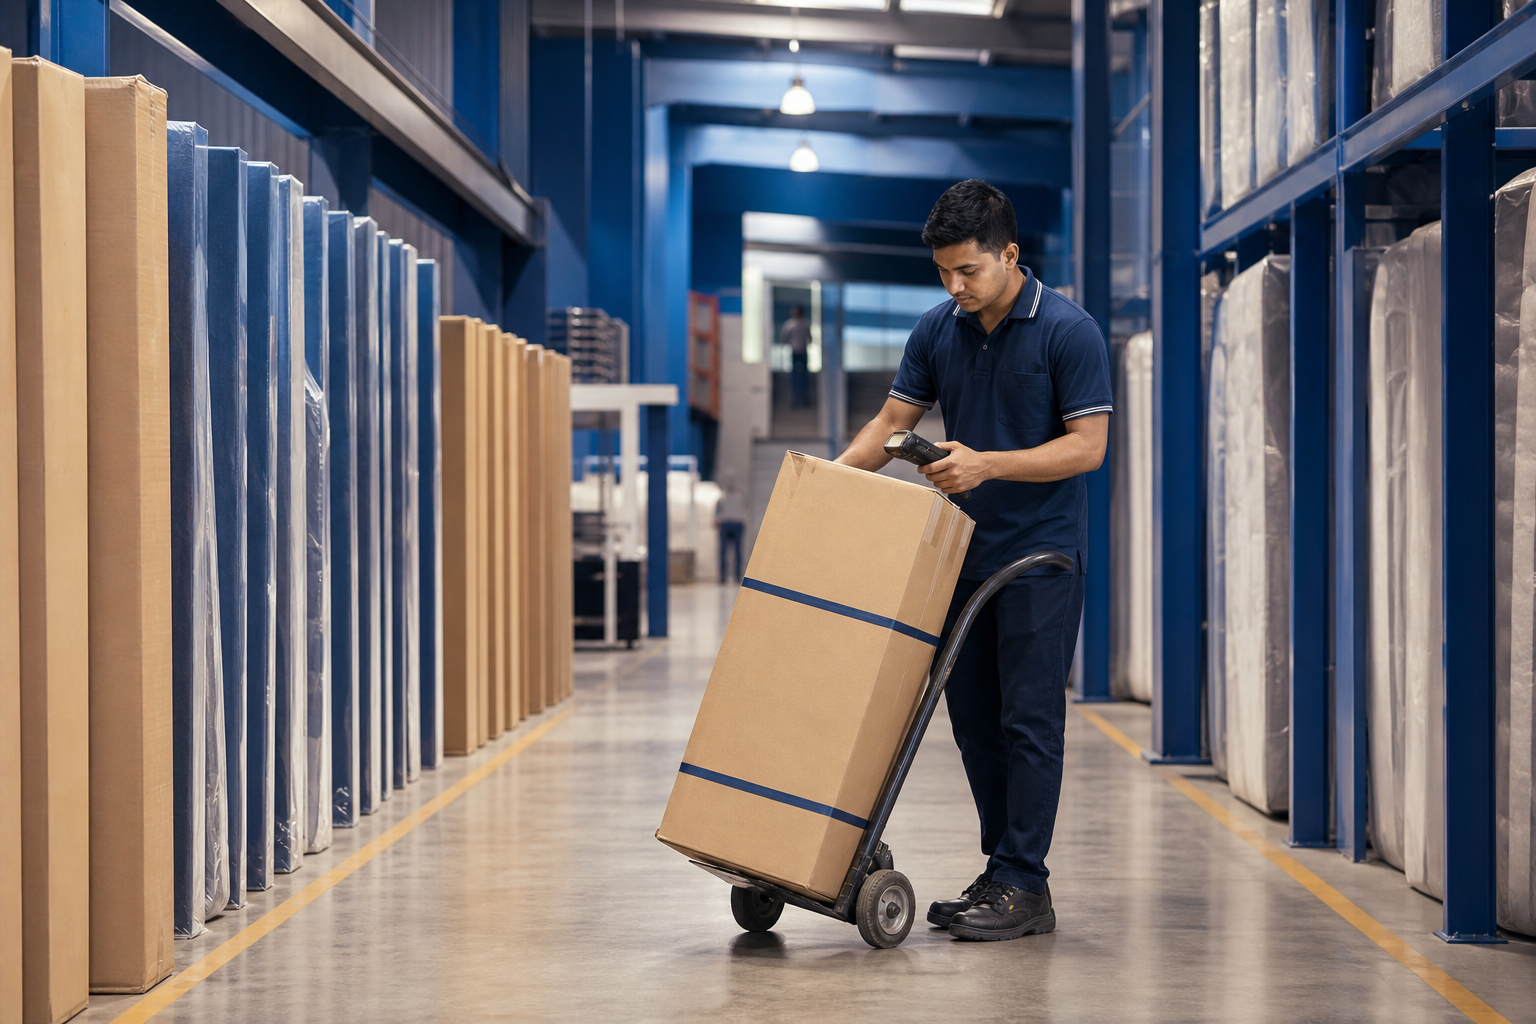
Wakefit, an Indian home and sleep solutions brand, operates in a category where the unit economics are very different from selling small parcels. A mattress, bed or sofa can require more storage space, careful handling, scheduled delivery, installation coordination and reverse logistics if the customer returns or exchanges the product.
The situation is classic cost to serve: online demand can come from many cities, but the fulfilment economics differ sharply by region. Dense metro clusters can support better route planning and fuller vehicles. Scattered demand may create higher delivery cost per order. Large-ticket items may absorb logistics cost better than low-ticket bulky items. Returns can be far more expensive than the original sale suggests.
The strategic move is to examine profitability by city cluster, product category, order size and delivery complexity rather than only by topline sales. A city with strong demand but high cost to serve may justify a local fulfilment node, store-led delivery, changed delivery promise, installation batching or different minimum order economics. A customer cohort with high returns may need better product information, fit guidance and service design before dispatch.
The lesson is not “logistics cost is high.” The sharper lesson is that profitability depends on a system: the primary driver is bulky-product fulfilment complexity, supported by regional demand density, product mix, return behaviour, delivery promise and warehouse placement. A good manager redesigns the service model; a weak manager only blames freight cost.
How AI Changes Cost to Serve Analysis by Customer and Region
AI improves cost-to-serve analysis because the messy part is not the formula; it is joining operational data from orders, warehouse systems, transport, customer service, returns and finance.
A practical student workflow: load a company annual report, a mock order dataset and your notes into NotebookLM, then ask it to generate “five cost-to-serve hypotheses by customer and region, with the cost driver and data field needed to test each.” For replenishment-heavy businesses, connect this thinking with using AI for inventory optimisation and replenishment, because inventory placement and service cost often move together.
Interview Relevance
“A company finds that its fastest-growing region is not improving operating profit. How would you use cost to serve analysis to diagnose the issue?”
Use the phrase “same revenue, different resource consumption.” It instantly signals that you understand why cost to serve is more powerful than a normal sales report.
Common Mistake
The mistake: allocating all logistics and service cost by revenue percentage. This hides the real problem because a small customer with many urgent orders may consume more resources than a large customer with consolidated orders. One-line fix: allocate cost using causal activity drivers - orders, lines, drops, kilometres, pallets, returns and service tickets.