
Cost Transformation Programmes and Zero-Based Budgeting
At 8:30 a.m., a warehouse control room is staring at the same problem from three screens: rising line-haul cost, overtime spikes, and customer promises that cannot slip. The lazy answer is “cut 10% everywhere”; the smart answer is to rebuild the cost base around what actually creates value.
- Cost transformation is not cost cutting. It redesigns spend, processes, operating model and governance so lower cost becomes sustainable.
- Zero-based budgeting asks each cost owner to justify spend from zero, instead of starting with last year’s budget plus inflation.
- The strongest programmes separate good cost that funds strategy from bad cost that adds complexity, rework or low-value activity.
- A practical cost programme moves through five stages: baseline, diagnose, design, execute, govern.
- ZBB works best on addressable spend such as marketing, travel, facilities, procurement, G&A, technology run-cost and discretionary operating expense.
- Track savings with real P&L impact: run-rate savings, realisation rate, drop-through, payback, cost-to-serve and service-level protection.
- The interview trap is recommending blanket cuts. Always protect growth, customer experience, compliance and critical capability.
Big Picture: Cost Transformation Is a Redesign, Not a Diet
Think of cost transformation as a structured reset of how money flows through the business. Zero-based budgeting is one powerful tool inside it, especially when legacy budgets have become “entitlements” rather than choices.
Core Explanation: The Cost Transformation Playbook
A cost transformation programme is a cross-functional effort to structurally reduce cost while protecting the activities that create customer value, revenue growth and risk control.
The word “structurally” matters. A hiring freeze or travel ban can reduce this quarter’s expense, but costs usually creep back. Transformation changes demand, process, policy, organisation design, sourcing, technology and accountability so the new cost base holds.
The Five-Step Process
In consulting cases, step one often begins with process mapping and finding the bottleneck, because many “cost problems” are actually hidden waiting time, rework, handoffs or capacity mismatch.
Where Zero-Based Budgeting Fits
Traditional budgeting starts with last year’s number and debates the increment. Zero-based budgeting starts with the activity and asks: “If we were building this cost today, what level would we approve?”
ZBB is especially useful when costs are sticky: recurring subscriptions, agency retainers, travel policies, meeting budgets, duplicated roles, low-usage tools, fragmented vendors, excessive service levels or “because we always do it” activities.
The Good Cost vs Bad Cost Decision Matrix
The best cost leaders do not ask, “What can we cut?” They ask, “Which cost buys strategic value, and which cost only buys complexity?”
This is why cost transformation must connect to strategy. A bank may protect fraud analytics while reducing branch paperwork. A retailer may cut slow-moving SKU complexity while investing in faster last-mile delivery. A SaaS company may reduce unused cloud instances while protecting product reliability.
A manufacturer with hundreds of small vendors may reduce cost through demand bundling, specification standardisation, should-cost analysis and competitive bidding. This is not just “negotiate harder”; the primary driver is spend consolidation, supported by clearer specifications, vendor competition and contract compliance. For deeper sourcing levers, revise procurement, sourcing and vendor negotiation levers.
Common Cost Levers and When to Use Them
Metrics That Prove the Programme Is Real
Cost transformation fails when dashboards celebrate “identified savings” but the P&L never moves. Use metrics that separate idea value, implemented value and business impact.
Worked Example: Turning a Cost Target Into a Real Plan
Suppose a logistics business has a ₹100 crore annual operating-cost baseline. Management wants a 12% structural reduction, so the target is ₹12 crore recurring savings.
The programme reaches ₹12 crore annualised savings with ₹3.7 crore one-time cost. Payback is ₹3.7 crore / ₹12 crore = 0.31 years, or roughly four months. But the recommendation is still incomplete unless you also specify which service levels must be protected.
Definitions You Can Say in One Breath
- Cost transformation: a structured redesign of cost, process, organisation and governance to create a sustainable lower cost base.
- Zero-based budgeting: a budgeting method where each activity and expense must be justified from zero for the new period.
- Cost baseline: the agreed starting view of spend against which savings are measured.
- Run-rate saving: the annual recurring saving expected once an initiative is fully implemented.
- Cost-to-serve: the total cost of serving a customer, channel, product or segment across the value chain.
Case Study: Delhivery’s Network-Led Cost Discipline
Delhivery shows how a cost transformation can come from network design, automation, utilisation and operating discipline rather than a simple spending freeze.
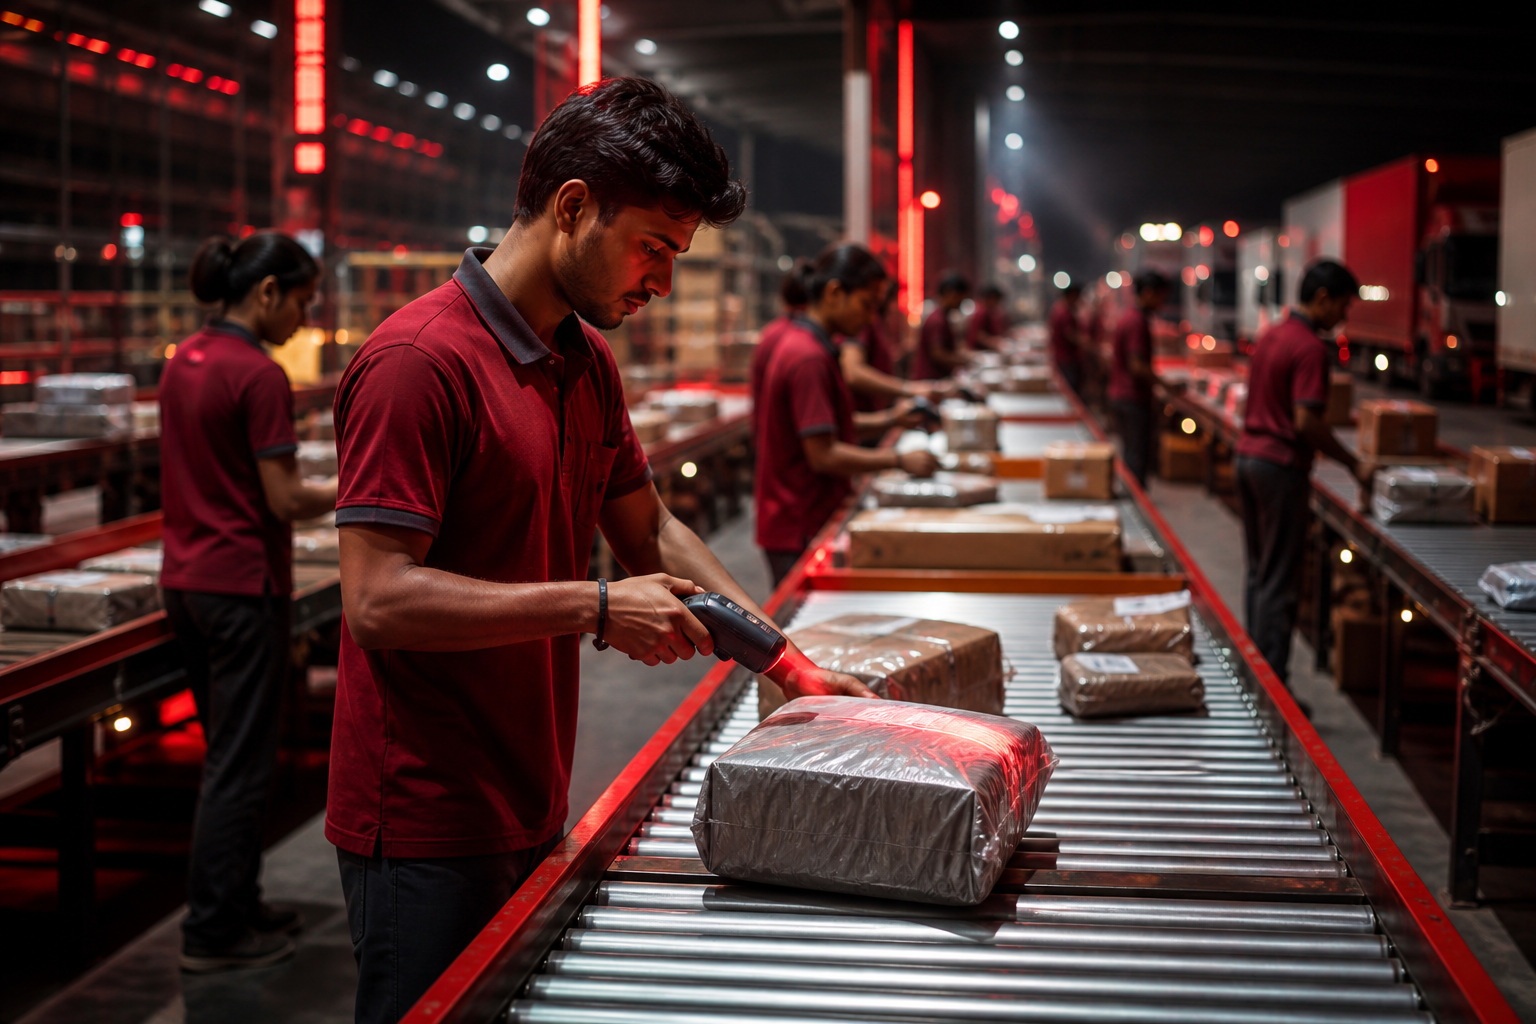
Situation. Logistics businesses carry high fixed and semi-fixed costs: sortation centres, line-haul capacity, delivery teams, technology infrastructure and local branches. When volumes fluctuate or networks overlap, cost per shipment can rise quickly even if demand is still growing.
The move. Delhivery’s public investor communications describe a business built around an integrated logistics network, technology-led operations and automated sortation capabilities (Delhivery Investor Relations). In cost-transformation language, the primary driver is network productivity: better utilisation of routes, hubs and sortation capacity. Supporting drivers include automation, data-led routing, facility rationalisation, operating standardisation and tighter control of cost-to-serve by shipment type.
The lesson. This is a stronger cost story than “reduce headcount” or “negotiate transport rates.” In network businesses, sustainable savings usually come from redesigning the system: where nodes are located, how volume is consolidated, how assets are utilised, and how exceptions are reduced.
The “so what” for interviews: if the business has physical flow - parcels, trucks, warehouses, stores, factories - do not jump straight to budget cuts. First test whether the network and process design are creating avoidable cost. The natural next case skill is reducing cost to serve without hurting service.
How AI Changes Cost Transformation Programmes and Zero-Based Budgeting
AI does not replace the cost-transformation logic; it makes the diagnosis faster and the governance sharper.
- Spend classification becomes faster. ML models can classify invoices, vendors and GL descriptions into a spend cube, helping teams spot fragmented vendors, duplicate tools and unusual price variance.
- Process mining becomes more powerful. AI can identify rework loops, exception paths and manual handoffs from system logs, then suggest where automation or standardisation will reduce cost.
- ZBB challenge packs become easier to build. GenAI can summarise each department’s activities, vendors, policies, volumes and prior-year spend so managers can challenge the “why” behind each cost line.
Use NotebookLM before a case discussion: upload the company annual report, a mock cost baseline and your case notes, then ask it to generate “five ZBB challenge questions by cost bucket” and “risks of cutting each bucket.” For AI-led operations case practice, pair this with automation and AI in operations consulting.
Interview Relevance
“A mid-sized consumer goods company’s operating margin has fallen despite stable revenue. The CEO wants a cost transformation programme. How would you structure the diagnosis, and where would zero-based budgeting help?”
Say this line in the interview: “I would not start with a percentage cut. I would first build the cost baseline, identify structural drivers, then choose levers that reduce bad cost while protecting growth and service.”
Common Mistake
The mistake: recommending a flat 10% cut across all departments. It sounds decisive but signals weak business judgement because it can damage revenue, compliance, service quality and critical capability. The fix: classify spend by value and controllability, then cut, redesign, protect or reinvest accordingly.