
Regulation and the Bodies That Govern E-Commerce & Quick Commerce
A 10-minute grocery order looks simple on the app: add milk, pay, track the rider, receive the bag. Behind that one checkout sit consumer protection rules, food safety norms, payment guidelines, data privacy law, packaging disclosures, FDI conditions and sometimes competition scrutiny.
That is why regulation in e-commerce and quick commerce is not “one ministry, one law.” It is a layered control system where each regulator sees a different risk in the same transaction.
- E-commerce regulation is layered: consumer protection, FDI, payments, data privacy, competition, food safety, legal metrology and sector-specific rules can all apply to one order.
- Quick commerce adds operational risk: dark stores, rider practices, perishable inventory, surge-like pricing, substitutions and instant refunds make compliance more real-time.
- India’s FDI policy matters: foreign investment is treated differently for marketplace and inventory-led e-commerce models under the DPIIT FDI policy.
- Consumer rules sit at the front door: product information, grievance redressal, refund clarity and seller details are core duties under India’s Consumer Protection (E-Commerce) Rules, 2020.
- Payments are not “just checkout”: gateways and aggregators fall under RBI oversight, including the RBI payment aggregator guidelines.
- Best interview answer: start with the business model, map the transaction journey, then attach the regulator at each risk point.
- Big mistake: naming regulators randomly instead of explaining what each one controls.
Big Picture: One Order, Many Regulators
Think of regulation as a funnel that narrows from business structure to customer harm. A platform first chooses a model, then acquires sellers, lists products, accepts payments, fulfils the order and resolves complaints. Each stage creates a different regulatory question.
This is the fastest way to sound structured in an interview: do not start with a list of laws. Start with the customer journey, then attach the relevant authority to each stage. If you need a wider method for mapping regulators in any sector, revise locating the regulator and what it controls.
Core Explanation: The Regulatory Stack for E-Commerce and Quick Commerce
E-commerce and quick commerce are regulated because platforms create trust at scale. Customers often do not know the seller, cannot inspect the product physically, pay digitally, share personal data and depend on fast fulfilment. Regulation reduces five risks: consumer harm, financial risk, data misuse, market power and sector-specific safety risk.
The Main Regulatory Bodies and What They Control
For interview purposes, remember this as a control map. The platform may be one app, but the regulatory questions are distributed across multiple authorities.
Two points separate strong candidates from average ones. First, e-commerce is not a “lightly regulated” space just because it is digital. Second, quick commerce is more operationally exposed than normal e-commerce because errors happen faster: wrong expiry, wrong pack size, missing invoice, cold-chain lapse, rider issue or instant refund dispute.
Marketplace vs Inventory Model: Why the Distinction Matters
India’s foreign investment rules make the business model especially important. Under the DPIIT FDI policy, e-commerce policy distinguishes between marketplace and inventory-based models, and that distinction affects what a foreign-funded platform can and cannot control.
E-commerce: “production, distribution, marketing, sale or delivery of goods and services by electronic means” - WTO Work Programme on Electronic Commerce.
Quick commerce: a retail model that fulfils small, frequent orders through hyperlocal inventory and rapid last-mile delivery.
Marketplace model: the platform connects buyers and third-party sellers without owning the sold inventory.
Inventory model: the platform owns or controls goods and sells them directly to customers.
In normal retail language, owning inventory sounds like better control. In Indian e-commerce policy, that control can become a regulatory issue if the entity has foreign investment and crosses into restricted inventory-led activity. That is why platforms spend so much time on seller structures, related-party arrangements, fulfilment contracts and discount mechanics.
How Regulation Changes in Quick Commerce
Quick commerce is not just e-commerce with faster delivery. It changes the compliance problem from periodic to real-time.
That is why a quick-commerce firm needs stronger internal controls than a typical app store. The operational promise - “fast” - increases regulatory exposure because mistakes scale before a human supervisor can intervene.
Regulatory Health Dashboard: What a Platform Should Track
If an interviewer asks “how would you monitor compliance?”, do not say “legal team will handle it.” Give a dashboard. Regulation becomes manageable when translated into measurable operating controls.
Use these metrics carefully. They are not statutory thresholds; they are management controls. The interview value is showing that you can convert regulation into operating discipline.
Mini Case Study: BigBasket’s Quick-Commerce Compliance Logic
BigBasket shows how a grocery platform must turn regulation into daily operating discipline when it moves from scheduled e-grocery to faster, dark-store-led fulfilment.
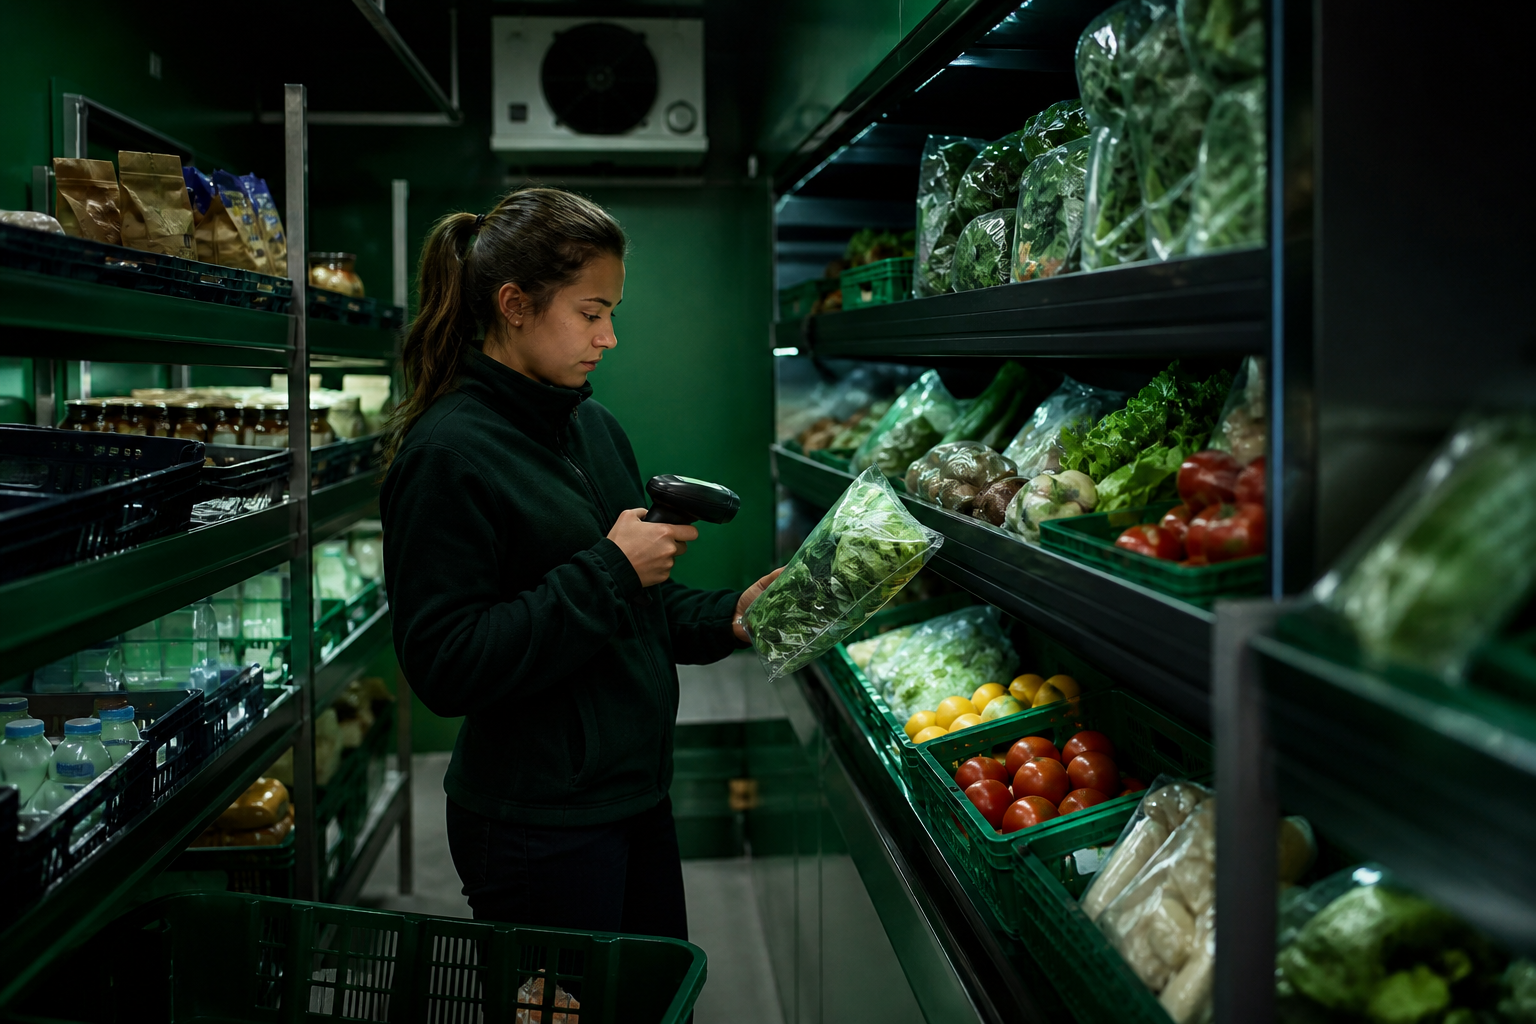
Situation. Online grocery has a heavier compliance burden than many other e-commerce categories because it involves food, packaged commodities, shelf life, substitutions, refunds and local fulfilment. When grocery platforms add faster delivery through hyperlocal inventory, every dark store effectively becomes a control point.
The move. BigBasket’s operating logic has to combine category-level compliance with fulfilment discipline: product listings need pack-size and MRP accuracy, food items need safety and licence checks under FSSAI rules, refunds must be visible to customers, and payments must flow through regulated checkout infrastructure. The primary driver is category-specific trust - customers buy food only when they believe quality and freshness are reliable. Supporting drivers are assortment control, inventory rotation, seller or vendor documentation, dark-store SOPs and customer-service workflows.
Outcome and lesson. The strategic lesson is not “BigBasket succeeds because it delivers fast.” A better answer is: faster fulfilment is valuable only when supported by compliance-ready inventory systems, accurate listings, food-safety controls and reliable grievance handling. In regulated categories, speed without control becomes a liability.
How AI Changes Regulation and the Bodies That Govern E-Commerce & Quick Commerce
AI is changing this topic in three concrete ways.
- Automated compliance monitoring: platforms can use computer vision and rules engines to detect missing MRP, expiry, unit quantity or licence fields before a product goes live.
- Risk scoring for sellers and SKUs: machine-learning models can flag sellers with repeated complaints, unusual refund spikes, suspicious reviews or documentation gaps.
- AI-driven consumer protection risk: personalised pricing, recommendations, chatbot refunds and automated substitutions create new questions around transparency, consent, bias and accountability under consumer and data-protection rules.
Use Perplexity or ChatGPT to create a regulator map for one company, but verify every legal claim from official regulator pages. Then use AI to research a sector without importing its errors by asking: “For each regulator, show the exact rule, the business activity it controls, and the source link.”
The important interview point: AI reduces monitoring cost, but it does not transfer accountability. If an AI chatbot gives the wrong refund commitment or an algorithm pushes non-compliant listings, the platform still faces the customer and regulator.
Interview Relevance
“Suppose you are advising a quick-commerce grocery platform entering a new Indian city. Which regulators and compliance issues would you check before launch?”
Use the phrase: “I would regulate the journey, not just the company.” It immediately signals that you understand why multiple bodies govern the same platform.
Common Mistake
The mistake: giving a scattered list - “RBI, SEBI, CCI, government, consumer court” - without explaining what each body controls. Why it costs marks: it sounds memorised and may include irrelevant regulators. One-line fix: name the business activity first, then the regulator responsible for that risk.