
Fintech & Payments Interview Questions With Model Answers
Fintech is often mistaken for “a cool app on top of banking.” The real business is less glamorous and more powerful: moving money safely, cheaply and repeatedly while regulators, banks, merchants, customers and fraudsters all pull the system in different directions.
- Fintech is technology-enabled innovation in financial services; payments is the movement of value between payer and payee.
- A strong answer separates the rail - UPI, cards, IMPS, wallets - from the business model - gateway, issuer, acquirer, PSP, aggregator, SaaS or lending overlay.
- Payment businesses win through a loop: more users, more merchants, more transactions, better risk data, higher trust, and lower unit cost.
- Interviewers test four things: ecosystem clarity, regulation awareness, unit economics, and your ability to apply it to a company.
- The metrics to remember are TPV, transaction success rate, take rate, CAC payback, fraud/dispute rate and uptime.
- Do not say “UPI has killed all payment companies.” It has shifted monetisation from pure MDR to software, credit, merchant tools and data-led services.
Big Picture: Payments Is an Ecosystem, Not an App
The cleanest way to revise fintech payments is to stop thinking “Paytm versus PhonePe versus Razorpay” and start thinking in layers: who initiates the payment, which rail carries it, who takes risk, who earns revenue, and who is regulated.
This is why sector knowledge matters. A candidate who can map the ecosystem will usually outperform someone who only lists popular apps; if this feels new, revise mapping a value chain and finding the profit pool before going deeper.
Core Explanation: The Fintech & Payments Mental Model
1. The Four Layers You Must Separate
Most weak answers mix up infrastructure, interface and monetisation. Use this four-layer stack instead.
2. The Payments Flywheel
Good fintech businesses do not win from one transaction. They win when repeated transaction data reduces risk, improves acceptance, lowers cost and attracts more merchants.
This loop also explains why payments alone can be low-margin, but payments plus merchant software, reconciliation, credit and loyalty can become a stronger business.
3. Business Models in Payments
When asked “How does this company make money?”, avoid one-line answers. Split revenue into transaction, platform and adjacent revenue.
4. Metrics Interviewers Expect You to Know
Payments is a metrics-heavy sector. Do not say “growth is good” vaguely. Name the metric, formula and business meaning. For a broader method, revise finding the metrics a sector is actually judged on.
5. Worked Mini Example: Why Volume Alone Is Not Enough
Suppose a payment gateway processes ₹100 crore of monthly TPV. Its net take rate is 0.20%, so monthly net revenue is:
₹100 crore × 0.20% = ₹20 lakh
If processing cost, support, risk losses and infrastructure together cost ₹14 lakh, gross contribution is ₹6 lakh. If the company spent ₹60 lakh acquiring this merchant cohort, CAC payback is:
₹60 lakh ÷ ₹6 lakh = 10 months
That is why interviewers push beyond TPV. A business can look large but still struggle if take rate is thin, risk cost is high or acquisition payback is too long.
Definitions You Can Say in One Breath
- Fintech: “Technologically enabled innovation in financial services” that may create new business models, applications, processes or products Financial Stability Board.
- Payment rail: The network and rules that carry payment instructions between participants.
- Payment aggregator: An intermediary that enables merchants to accept payments from customers through multiple payment modes.
- Take rate: Net revenue earned as a percentage of total payment value processed.
Model Answers to Common Fintech & Payments Interview Questions
Use these as patterns, not scripts. A good answer has structure, one real example and one trade-off.
Question 1: How do fintech payment companies make money when UPI is free for users?
Model answer: I would separate user pricing from company monetisation. In many payment flows, the consumer may pay nothing, but the company can earn from merchant services, payment gateway fees on applicable rails, software subscriptions, reconciliation tools, lending, loyalty, device rentals or enterprise payouts. The key is that payments create frequent interaction and data; monetisation often comes from solving adjacent business problems for merchants. So the better question is not “Is the payment free?” but “What workflow does the payment company own after the transaction?”
Question 2: Explain UPI's impact on Indian fintech.
Model answer: UPI expanded digital payment adoption by making bank-to-bank payments simple, interoperable and mobile-first. The impact is two-sided: it increased transaction volume and habit formation, but also made pure payment monetisation harder for many consumer apps. As a result, fintechs have moved toward merchant solutions, credit, wealth, insurance distribution, SaaS tools and higher-value payment flows. The strategic lesson is that open infrastructure can grow the market while compressing margins at the interface layer.
Question 3: What is the difference between a payment gateway and a payment aggregator?
Model answer: A payment gateway is the technology layer that securely captures and routes payment information. A payment aggregator goes further by onboarding merchants and enabling them to accept multiple payment modes, often without each merchant creating separate direct relationships with every bank or network. In practice, many companies offer both capabilities, so I would check the exact regulatory role, settlement responsibility and merchant relationship before labelling the business.
Question 4: What risks does a payments company manage?
Model answer: I would group risks into five buckets: fraud risk, settlement risk, operational downtime, regulatory non-compliance and customer trust risk. For example, a payment aggregator must onboard merchants carefully, monitor suspicious transaction patterns, ensure timely settlement and maintain high system availability. The best companies balance risk control with conversion; if fraud rules are too strict, genuine customers fail, but if rules are loose, losses and regulatory scrutiny rise.
Question 5: How would you evaluate a fintech company before joining it?
Model answer: I would evaluate it on five dimensions: regulatory permissions, target customer segment, unit economics, risk controls and path to profitable scale. I would ask whether growth comes from durable merchant relationships or only incentives, whether take rate covers variable costs, whether fraud and disputes are controlled, and whether the company has an adjacency like SaaS, credit or cross-border payments. This converts the evaluation from brand popularity to business quality.
Case Study: Pine Labs and the Merchant Payments Play
Pine Labs shows how a payments business can move beyond transaction acceptance into merchant commerce infrastructure.
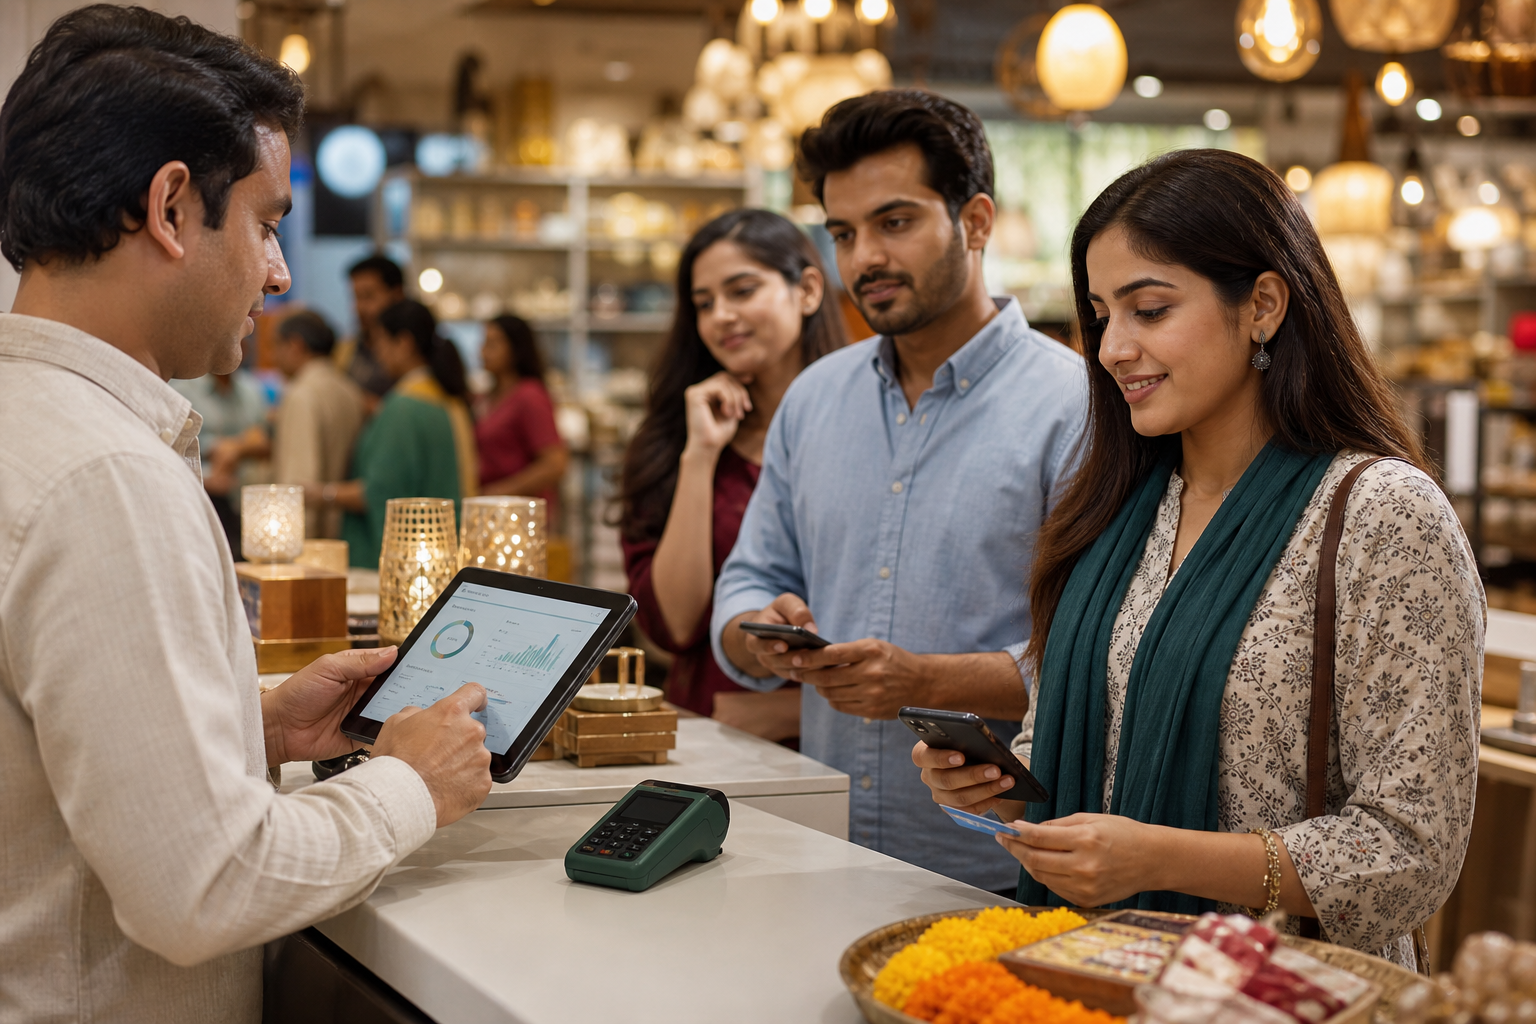
Situation: Indian merchants needed to accept more digital payments, but payment acceptance alone was becoming a thin-margin, competitive service. Offline retailers also needed reconciliation, affordability offers, loyalty, billing integration and later omnichannel capabilities.
The move: Pine Labs built around the merchant point of sale and expanded from card acceptance into commerce enablement: POS software, payment acceptance, pay-later or EMI-led affordability journeys, merchant analytics and enterprise integrations. The primary driver was ownership of the merchant checkout workflow. Supporting drivers included bank and brand partnerships, offline distribution, enterprise merchant relationships and the ability to add software services around the payment event.
Outcome / lesson: The lesson is not “Pine Labs wins because it has POS machines.” The stronger insight is that control over a high-frequency merchant workflow creates opportunities to attach payments, software, credit, loyalty and analytics. In fintech interviews, this is the difference between describing a product and understanding a profit pool.
How AI Changes Fintech & Payments
AI is not just adding chatbots to fintech apps. It is changing underwriting, fraud control, operations and customer service where payment data is frequent and behaviour-rich.
Use NotebookLM or ChatGPT like an analyst, not a shortcut. Load a company annual report, product pages and regulator notes, then ask: “Map this fintech into customer segment, payment rail, revenue model, risk controls, competitors and three likely interview questions.” Cross-check every factual output using reliable sources; this is exactly where using AI to research a sector without importing its errors matters.
Interview Relevance
“Pick any Indian fintech payments company. Explain its business model, key risks, and whether you think it can become profitable.”
If you are unsure about a company, answer from first principles: “Let me map the ecosystem first.” That sounds far stronger than guessing a revenue number.
Common Mistake
The biggest mistake is treating fintech as a consumer-app popularity contest. It costs candidates because interviewers are testing business model, regulation and unit economics. One-line fix: always answer in this order - customer, rail, revenue, risk, metric, strategic trade-off.