
Key Players and the Competitive Map in Energy & Renewables
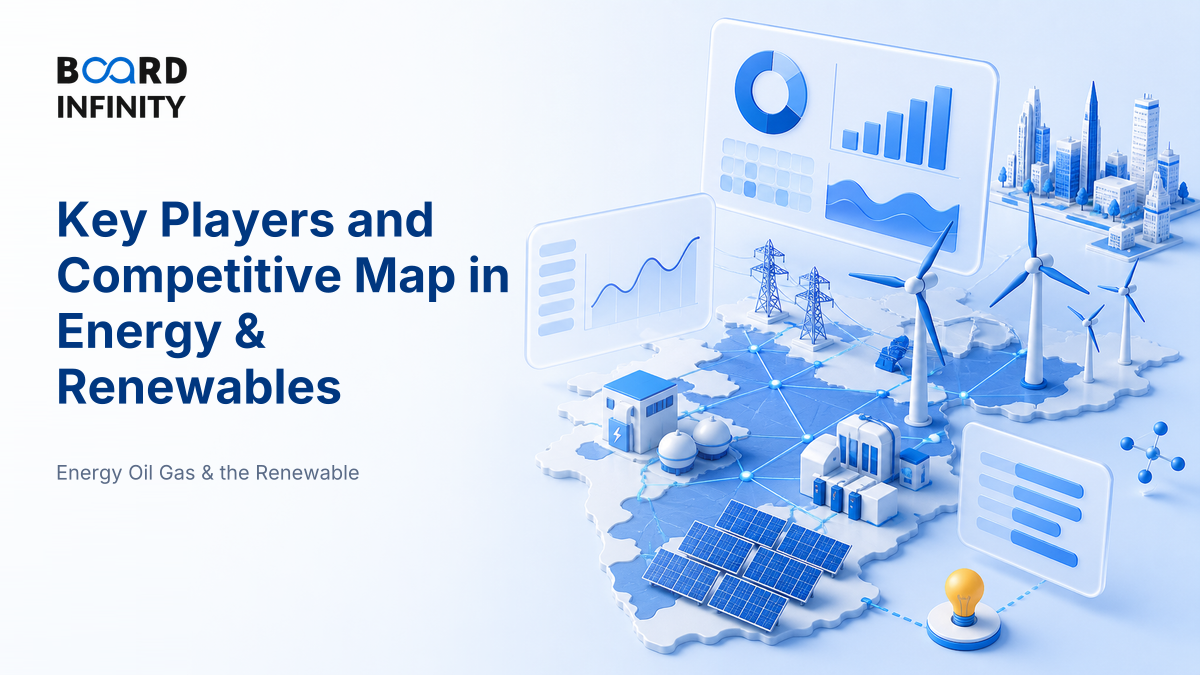
A solar farm looks simple from the highway: panels, land, sunlight. But the real competition may be between a module maker in Gujarat, a power trader, a state DISCOM, a private industrial buyer, a lender, and a developer bidding for the same long-term contract.
That is the surprise in energy and renewables: the company you see producing electricity is often not the company with the strongest competitive control. The winner is usually the player that controls the scarce bottleneck - land, grid access, low-cost capital, equipment supply, customer demand, or regulatory permission.
- Energy is not one industry. It is a system of fuel, equipment, projects, grids, contracts, finance, and customers.
- Map players by value-chain position first: resource owners, OEMs, EPCs, generators, grid/distribution firms, traders, financiers, and end customers.
- Renewables competition is contract-led. A solar or wind asset is only as attractive as its tariff, offtaker quality, grid connectivity, and financing cost.
- Old energy and new energy overlap. Oil and gas firms, utilities, renewable IPPs, battery firms, and green hydrogen players increasingly compete for the same energy wallet.
- The strongest player is not always the largest MW owner. Advantage can sit with low-cost manufacturers, grid owners, C&I customer platforms, or firms with cheap capital.
- Interview answer rule: never list companies randomly; place each company on the value chain and explain its source of power.
The Big Picture: Energy Is a Chain, Not a List of Companies
To understand the competitive map, think of energy as a left-to-right conversion system: natural resources and capital become equipment, projects, electrons, contracts, and finally customer bills. Each stage has different economics and different key players.
Core Explanation: How to Read the Competitive Map
A competitive map shows who competes, where they sit in the value chain, and what source of advantage they defend. In energy and renewables, the best map answers three questions:
This matters because energy companies can look similar on the surface but have very different risk profiles. A solar module manufacturer, a renewable independent power producer, a DISCOM, and a power exchange are all part of renewables, but they do not compete on the same capability.
The Main Player Groups in Energy & Renewables
Use this map in interviews. It prevents the common mistake of saying “NTPC, Tata Power, Adani Green, ReNew” without explaining what each actually does.
The sharper answer is not “Company X is in renewables.” The sharper answer is: “Company X is a renewable IPP with advantage in project execution and capital access, but its risk depends on tariffs, offtaker quality, and grid curtailment.”
The Four Sources of Competitive Power
In energy, advantage usually comes from one or more of four control points. This is the mental model interviewers like because it separates serious candidates from headline readers.
Asset control means owning or accessing scarce physical assets: transmission corridors, renewable sites, mines, LNG terminals, or storage assets. Cost control means producing or procuring energy cheaper than rivals. Contract control means locking in reliable cash flows through power purchase agreements, open-access customers, or regulated returns. Regulatory control means understanding approvals, tariffs, grid rules, renewable purchase obligations, and state-level charges.
If you are researching a company, start by reading its segment notes, capacity pipeline, customer concentration, receivables, and capital expenditure plan. A quick method is covered in Reading an Annual Report for Sector Insight.
The Competitive Map: Regulated vs Market-Exposed, Asset-Heavy vs Asset-Light
A useful way to place energy players is to ask two questions: how asset-heavy is the model, and how exposed is it to market prices versus regulation or contracts?
This matrix is especially useful when comparing a power exchange with a renewable IPP, or a DISCOM with a battery analytics company. They may all benefit from electrification, but their risks are not the same.
The Metrics That Reveal Competitive Strength
You do not need to memorise every energy ratio. You need enough metrics to diagnose whether a player’s position is strong, fragile, or misunderstood.
Notice the logic: a renewable company can report fast capacity growth and still be risky if tariffs are aggressive, receivables are stretched, leverage is high, or grid curtailment is rising. Growth and quality must be read together.
Definitions You Must Be Able to Say Cleanly
- Competitive map: a view of where firms compete, how they make money, and what advantage each controls.
- IPP: an independent power producer that owns generation assets and sells electricity to utilities, exchanges, or customers.
- PPA: a power purchase agreement that fixes commercial terms between a generator and electricity buyer.
- DISCOM: a distribution company that buys power and supplies it to end consumers in a licensed area.
- LCOE: levelised cost of electricity, or the average lifetime cost of producing one unit of power.
- Five Forces: Porter’s Five Forces explain industry pressure through rivalry, entrants, substitutes, buyer power, and supplier power.
Case Study: Serentica Renewables and the C&I Energy Map
Serentica Renewables shows how a renewable player can compete around industrial customer demand, not only around utility-scale generation.
Serentica Renewables positions itself as a renewable energy platform for commercial and industrial customers, a segment where buyers want cleaner power but also care deeply about reliability, cost visibility, and regulatory execution. That makes it a strong case for understanding the competitive map beyond “solar versus coal.”
Situation: Large industrial users in India face pressure to decarbonise operations while keeping power costs predictable. Buying renewable power is not as simple as installing panels. It involves open-access permissions, state-level charges, grid scheduling, balancing, and contract structuring.
The move: Serentica focuses on C&I offtake - supplying renewable power to energy-intensive corporate customers. The primary driver is a clear customer wedge: industries need credible decarbonisation without losing supply reliability. Supporting drivers include portfolio design across renewable sources, long-term contracts, open-access regulatory know-how, and access to infrastructure capital.
The lesson: In renewables, the winning position may be closest to the customer rather than closest to the sun or wind. A C&I platform competes by solving procurement, reliability, and compliance pain points for industrial buyers. That is different from a pure merchant generator, a solar module maker, or an EPC contractor.
How AI Changes Energy & Renewables Competitive Mapping
AI is changing the sector map in three practical ways.
- Forecasting becomes a competitive edge. Renewable output depends on weather, seasonality, and grid conditions. AI improves generation forecasting, demand prediction, and scheduling decisions, which can reduce imbalance risk.
- Project screening gets faster. AI tools can combine satellite imagery, weather data, grid proximity, land constraints, and policy documents to shortlist potential solar, wind, storage, or green hydrogen locations.
- Competitive intelligence becomes continuous. Analysts can track tenders, tariffs, policy orders, annual reports, credit-rating notes, and earnings-call transcripts to see which players are gaining pipeline, capital, or customer access.
Student workflow: Use NotebookLM or Perplexity to build a two-page company brief. Load the company annual report, investor presentation, and recent regulatory order; ask: “Map this company across the energy value chain, identify its revenue model, list its top risks, and compare it with two Indian peers.” Then verify every figure from the original document. For safe AI research habits, revise Using AI to Research a Sector Without Importing Its Errors.
Interview Relevance
“Map the key players in India’s energy and renewables sector. Where is competition most intense, and where can companies build durable advantage?”
If the interviewer names a company, do not rush to its stock performance. First locate its business model on the map, then discuss its advantage and risk. For regulation-heavy answers, use Locating the Regulator and What It Controls to structure who governs what.
Common Mistake
The biggest mistake is treating “renewables” as a single bucket and listing famous companies. It costs candidates because it hides the real economics: a module maker, IPP, DISCOM, trader, and C&I platform have different margins, risks, and moats. Fix: always answer by value-chain position plus source of competitive power.