
Indian Market Nuances in Energy & Renewables
A solar project in Rajasthan can look perfect on paper - high irradiation, falling module costs, a long-term buyer - and still get stuck because the evacuation line is delayed or the DISCOM’s payment cycle weakens the project economics. That is the Indian energy market in one scene: the opportunity is huge, but the winning answer is never just “renewables are growing.” It is “who buys, who regulates, who pays, and can the grid absorb it?”
- India’s energy market is federal, not uniform: central policy sets direction, but state regulators, DISCOMs and local charges shape project economics.
- Renewables are not just a generation story: land, evacuation, storage, forecasting, curtailment and buyer creditworthiness decide real returns.
- DISCOM economics is the hidden lever: payment delays, tariff cross-subsidy and AT&C losses affect power producers, C&I buyers and consumers.
- Open access is a major Indian nuance: companies can buy power directly, but the landed cost depends on wheeling, banking and cross-subsidy charges.
- Segment before you opine: utility-scale solar, rooftop, C&I open access, rural mini-grids, storage and green hydrogen follow different business models.
- The best interview answer uses four lenses: resource, grid, buyer, regulation and capital - in that order.
Big Picture
India’s energy transition is not a straight line from coal to solar. It is a layered market where policy ambition must pass through state-level regulation, grid capacity, buyer payment risk and project finance before it becomes a bankable business.
The Core Logic: Why India’s Energy Market Behaves Differently
The simplest way to analyse Indian energy and renewables is to avoid a technology-first answer. Solar, wind, batteries and green hydrogen matter - but in India, the market often turns on institutional design: who controls tariffs, who owns distribution, who bears losses, and who pays on time.
Use this five-part diagnostic for any company, project or policy in the sector.
1. Resource is necessary, but not sufficient
India has strong solar and wind potential in several regions, but a good resource zone is not automatically a good business. A solar park with high irradiation still needs land acquisition, transmission evacuation, predictable scheduling and a buyer with payment discipline.
2. The grid is the bottleneck between policy and revenue
Renewable generation is variable. That means the value of a project depends on whether the grid can absorb power when it is generated. Interviewers like this nuance because it separates a superficial “renewables will grow” answer from a sector-ready answer.
The grid question has three parts:
3. DISCOMs are the commercial centre of the system
Distribution companies, or DISCOMs, buy power, sell it to end-users and collect revenue. Many sector answers fail because candidates jump from generation capacity to demand without analysing DISCOM finances. If the DISCOM cannot recover costs through tariffs or collections, the stress travels backward to generators and lenders.
For regulatory mapping, revise how to locate the regulator and what it controls - energy is one of the best sectors to practise that skill because central and state institutions both matter.
4. Open access changes the buyer map
Under India’s Electricity Act, 2003, open access allows eligible consumers to use transmission or distribution networks to buy power from a supplier other than the local distribution licensee (Ministry of Power, Electricity Act 2003). In plain English: a factory may try to source renewable power directly instead of buying all electricity from the DISCOM.
But the interview nuance is this: open access is attractive only when the landed cost beats the grid tariff after adding wheeling charges, banking charges, transmission losses, cross-subsidy surcharge and reliability risk.
5. Capital follows bankability, not announcements
Energy projects are capital-intensive. A lender or investor will not fund a project just because the theme is attractive. They look at contracted tariff, buyer credit, expected generation, curtailment protection, debt service ability, and regulatory stability. To practise extracting these signals from company documents, use the method in reading an annual report for sector insight.
Key Metrics to Track in Energy and Renewables
Use metrics to show commercial maturity. Do not say “the project is viable” until you can say which metric proves it.
Worked example - CUF: Suppose a 100 MW solar plant generates 180,000 MWh in a year. Maximum possible generation is 100 MW × 8,760 hours = 876,000 MWh. CUF = 180,000 / 876,000 = 20.5%. The next question is not “is 20.5% good in general?” It is “does it beat the plant’s contracted base-case generation for that location and technology?”
Definitions You Should Be Able to Say Cleanly
- Renewable energy: “Energy derived from natural sources that are replenished at a higher rate than they are consumed” (United Nations).
- Energy security: “The uninterrupted availability of energy sources at an affordable price” (International Energy Agency).
- DISCOM: A distribution company that buys electricity, distributes it locally and collects payment from end consumers.
- Open access: A mechanism allowing eligible consumers to buy electricity using the grid from a supplier other than the local DISCOM.
- C&I renewables: Renewable energy sold to commercial and industrial buyers, often through rooftop, captive or open-access structures.
Case Study: Husk Power Systems and the Indian Mini-Grid Nuance
Husk Power Systems shows why India’s renewable opportunity is not only utility-scale solar - it is also reliability, local demand creation and last-mile energy economics.
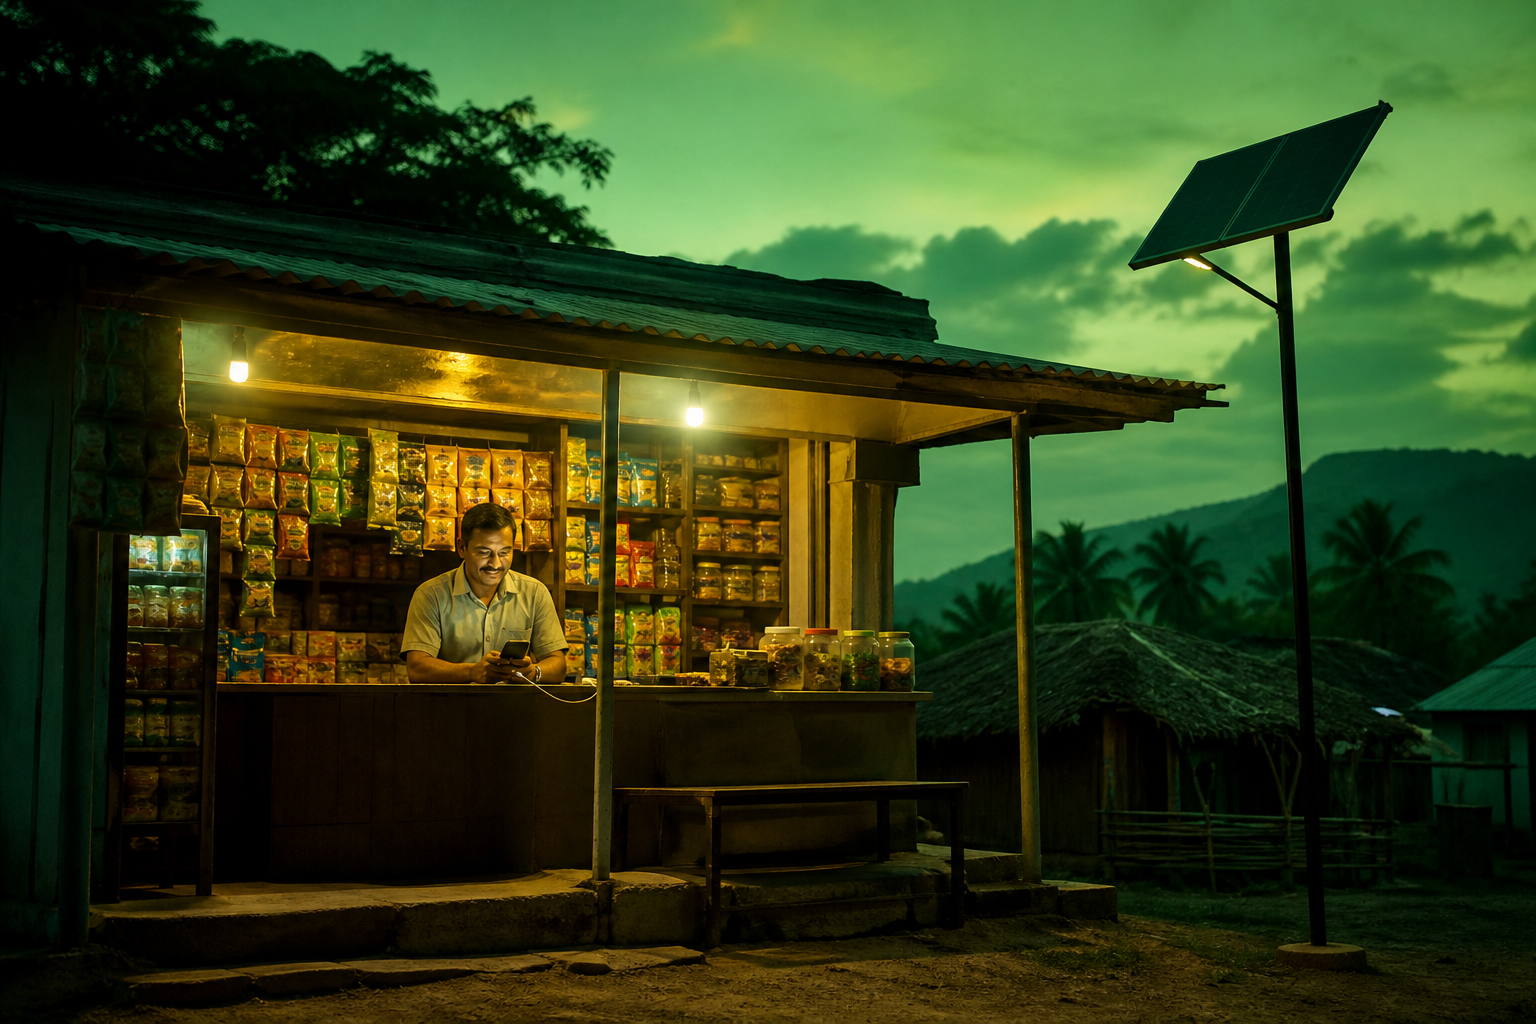
Situation: Many rural and semi-rural users do not only need “green power”; they need reliable, usable power at the point of consumption. In weak-grid locations, the problem is not just generation cost. It is availability, collections, local operations and whether electricity creates income-generating demand.
The move: Husk built a decentralised mini-grid model rather than behaving like a pure equipment seller. The primary driver is local reliability: power is generated and managed close to the customer. Supporting drivers include local operating presence, demand aggregation across households and small businesses, prepaid or disciplined collection models, and productive-use loads such as shops, small machinery or refrigeration.
The lesson: In India, renewables can win through centralised scale or through decentralised fit. Husk’s case teaches a high-value interview point: in energy access markets, the product is not a solar panel; the product is reliable electricity plus a payment and service model that the customer can actually use.
So what: A shallow answer says “mini-grids work because solar is cheaper.” A stronger answer says they work when lower energy cost is combined with local reliability, productive demand, collections discipline and operating service quality.
How AI Changes Indian Market Nuances in Energy & Renewables
AI does not remove India’s regulatory and grid constraints. It helps firms see them earlier, price them better and operate around them more intelligently.
Student workflow: Put a company annual report, a state tariff order summary and your own notes into NotebookLM. Ask: “Create five interview questions on the company’s renewable energy strategy, DISCOM exposure, open-access risk and project finance metrics. For each answer, show the source paragraph.” Then cross-check the output using the discipline in using AI to research a sector without importing its errors.
Interview Relevance
“India has ambitious renewable energy plans. What are the India-specific challenges and business opportunities in this sector?”
If the interviewer says “renewables,” immediately ask yourself: utility-scale, C&I, rooftop, storage or rural access? The answer changes completely by segment.
Common Mistake
The biggest mistake is giving a generic climate-tech answer - “India has sun, so solar will grow.” It costs candidates because it ignores the real Indian levers: DISCOM payments, state regulation, grid evacuation, open-access charges and project finance. One-line fix: always answer with the chain resource → grid → buyer → regulation → capital.